Beyond housing, regional underlying inflation is remarkably similar
Once housing is excluded, state inflation outcomes look strikingly alike, despite large differences in economic growth, labour market conditions and income growth.
- Underlying inflation is remarkably similar across the states despite, at times, very different economic conditions. Indeed, once housing is excluded, state measures of underlying inflation are strikingly close even in periods when there are large differences in growth, labour market conditions, household incomes and unit labour costs. This suggests that outside the housing sector, supply is generally able to respond relatively quickly to regional demand pressures as traded goods, and much domestic production, relies on national supply chains.
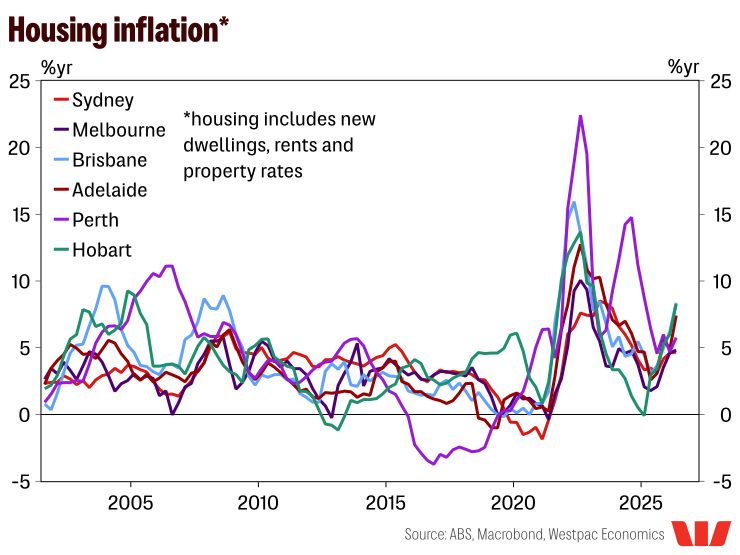
- Where there are divergences, housing costs have accounted for around half of the gap in underlying inflation since 2000 and more than 60% of the divergence during the mining boom. Housing supply responds slowly to demand shocks, making inflation outcomes more dependent on local demand conditions.
- The mining boom showed that labour inflows helped contain broader inflation pressures but also intensified housing demand and related inflation. Today's data centre and renewables investment boom (see here) is less likely to drive large population shifts, but competition for construction labour, materials and housing supply could generate an inflationary impulse.
As our Coast to Coast report has highlighted over the years, economic conditions can vary significantly across states. However, many of these differences narrow over time, partly as associated price and wage differences encourage individuals and businesses to adjust. That process can differ depending on the exact nature of imbalances across states. Here we take a closer look at how inflation has behaved across states, where gaps have emerged in the past and where they have tended to be more material and persistent. This, in turn, may provide some clues about the drivers of cycles in underlying inflation nationally.
A difficulty with this comparison is that headline inflation measures are heavily distorted by state specific government policy. Cost-of-living measures, including energy rebates and housing-related interventions, have had a significant influence on CPI outcomes in recent years. To look through these effects, we construct state-level measures of underlying inflation, including a housing-adjusted trimmed mean that excludes new dwelling purchase costs, rents and property rates.
The chart below shows our estimates of trimmed mean inflation across the capital cities (which we use as proxies for states). They reveal significant differences in underlying inflation over time. The clearest sustained differences are around the surge in inflation in WA and Qld in the initial stages of the mining boom of the mid-2000s, and the subsequent period of markedly lower inflation (including a brief period of deflation) in WA during the mid-2010s. However, divergences have generally been short-lived, with state inflation outcomes eventually converging towards the national pulse.
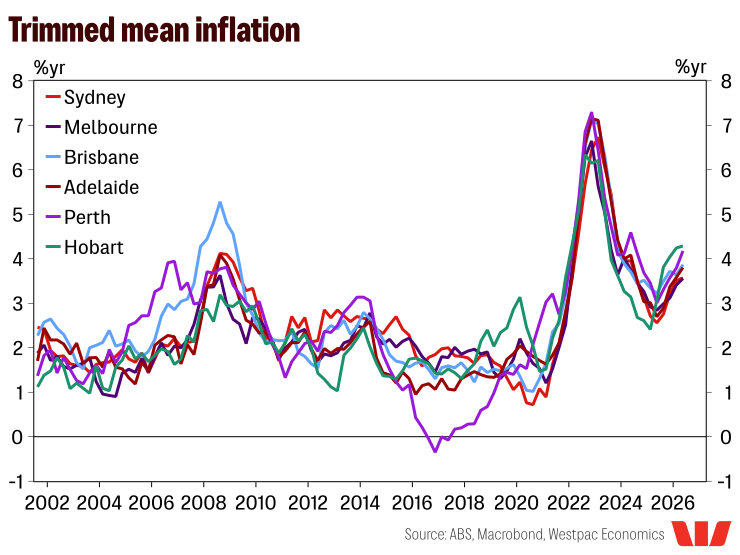
For the most recent periods, the trimmed mean measures effectively strip out the noise coming from cost-of-living measures (as per the national measure). The state TMs show underlying inflation has accelerated across all jurisdictions. But there are some significant variations with Vic recording the lowest rate of underlying inflation (3.6%yr) in Q2 and Tas the highest (4.3%yr).
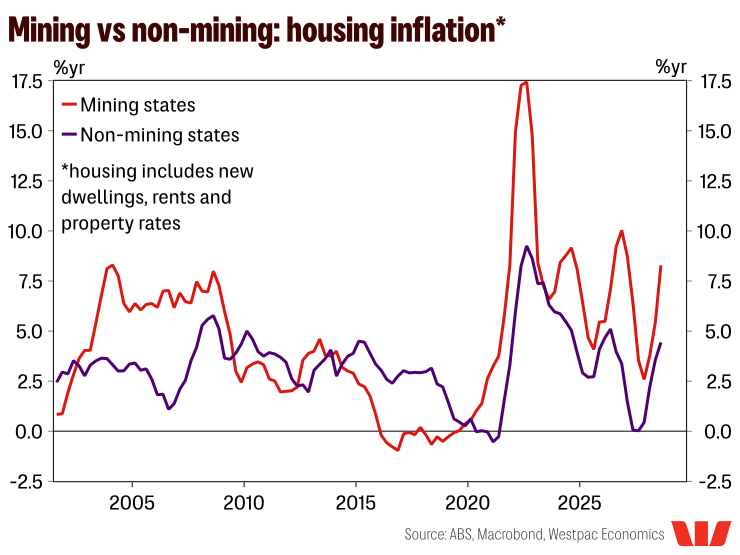
Much of this remaining variation comes from housing-related components (new dwellings, rents and property rates). Indeed, we estimate that these components account for around 50% of the underlying inflation gap between states since 2000, and over 60% of the gap during the mining boom.
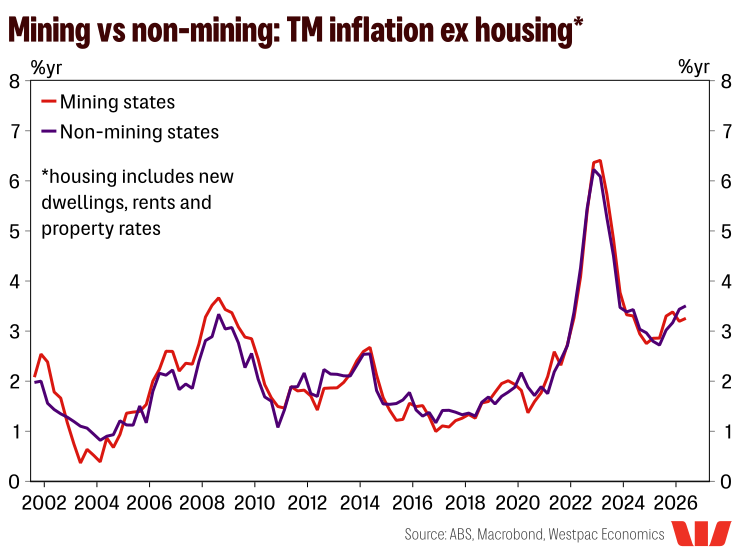
We can see this visually by stripping out housing components from our TM measures. As the chart below shows, the difference across states largely disappears when we look at underlying inflation (ex-housing).
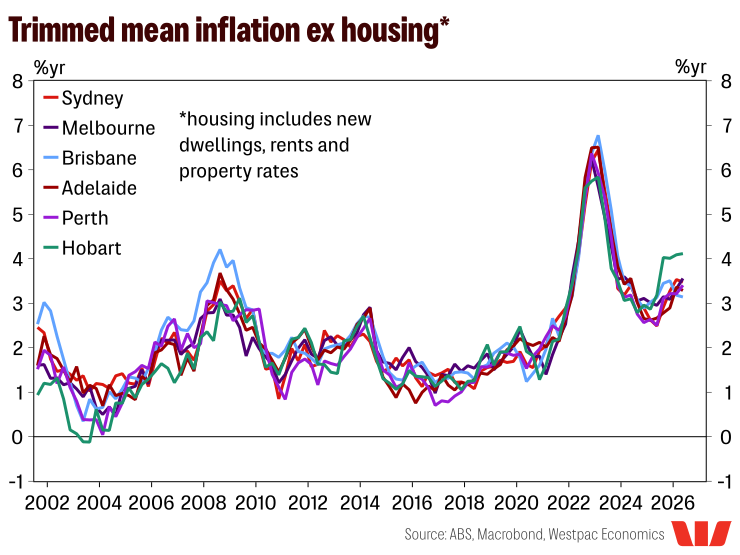
Importantly, these results provide valuable clues about the drivers of inflation, both today and into the future. Despite substantial variation in economic conditions, income growth and labour market outcomes across states, underlying inflation excluding housing has remained remarkably similar across state. This suggests that, outside the housing sector, supply is generally able to adjust to variations in demand across states relatively quickly, ‘equalising’ the impact on price inflation.
Clues from the mining investment cycle?
Why would state variations in housing costs be more persistent? The mining investment cycle may offer some insights here.
The boom phase of the mining investment cycle saw dramatic rises in commodity prices in its early stages with windfall gains for miners, some of which passed on to household and government incomes (including via share holdings). As the surge in investment mobilised, supply constraints started to emerge, particularly in the construction sector. Notably, differences in wage inflation (and unit labour costs) between the mining and non-mining states are somewhat starker and more sustained than for broader inflation. The stronger employment and wage gains added to the state wedge in household income growth. However, it also drew a supply response. Surging international and inter-state migration flows saw population growth hit 3.5%yr in WA with labour supply also significantly augmented by the use of ‘fly-in-fly-out’ workers travelling inter-state.
For housing, the situation is more difficult. Supply responses are slow at the best of times but faced intense competition for inputs from mining-related activity, particularly labour but also some locally-sourced material inputs. Meanwhile the population shift was pumping up housing demand. Perth’s rental vacancy rate, which was around 4% coming into the boom, dropped to just 1.4% by 2007. With incomes also rising, the combination saw both the city’s rents and established dwelling prices surge at a strong double-digit growth rate that lasted the best part of five years.
These dynamics reverse during the downturn phase of the cycle. And again, the effects can be more lasting for housing related costs, as the turnaround in migration flows and a lagged rise in housing supply amplifies the income effects from the investment wind down.
Fast forward to today
As data centre and renewable energy investment accelerates, the key inflation risk may not be stronger demand itself but the extent to which it spills over to the construction side of the housing sector. The data centre and renewables boom has a very different geographic pattern that suggests population shifts are unlikely to present the same challenges they did during the mining boom. It is also unlikely to draw in international migrants in the way the mining boom did either.
However, the competition for labour and locally-sourced construction materials will be the key factor. And construction capacity, labour and housing supply are all coming into this cycle from a tighter starting point than in the early 2000s, suggesting even modest increases in demand for construction services could generate a significant inflationary impulse.
While that leaves some open questions, the general takeaway from this analysis of state inflation trends is that housing related components of the CPI are the ones to keep an eye on when assessing how these developments may be influencing underlying inflation trends.
Stay informed with Westpac IQ
Get the latest reports straight to your inbox.
Related articles

Activities diverge but prices remained merged
Weekly Economic Commentary 21 Sep 2026
Browse topics
Disclaimer
©2026 Westpac Banking Corporation ABN 33 007 457 141 (including where acting under any of its Westpac, St George, Bank of Melbourne or BankSA brands, collectively, “Westpac”). References to the “Westpac Group” are to Westpac and its subsidiaries and includes the directors, employees and representatives of Westpac and its subsidiaries.
Things you should know
We respect your privacy: You can view the New Zealand Privacy Policy here, or the Australian Group Privacy Statement here. Each time someone visits our site, data is captured so that we can accurately evaluate the quality of our content and make improvements for you. We may at times use technology to capture data about you to help us to better understand you and your needs, including potentially for the purposes of assessing your individual reading habits and interests to allow us to provide suggestions regarding other reading material which may be suitable for you.
This information, unless specifically indicated otherwise, is under copyright of the Westpac Group. None of the material, nor its contents, nor any copy of it, may be altered in any way, transmitted to, copied of distributed to any other party without the prior written permission of the Westpac Group.
Disclaimer
This information has been prepared by Westpac and is intended for information purposes only. It is not intended to reflect any recommendation or financial advice and investment decisions should not be based on it. This information does not constitute an offer, a solicitation of an offer, or an inducement to subscribe for, purchase or sell any financial instrument or to enter into a legally binding contract. To the extent that this information contains any general advice, it has been prepared without taking into account your objectives, financial situation or needs and before acting on it you should consider the appropriateness of the advice. Certain types of transactions, including those involving futures, options and high yield securities give rise to substantial risk and are not suitable for all investors. We recommend that you seek your own independent legal or financial advice before proceeding with any investment decision.
This information may contain material provided by third parties. While such material is published with the necessary permission none of Westpac or its related entities accepts any responsibility for the accuracy or completeness of any such material. Although we have made every effort to ensure this information is free from error, none of Westpac or its related entities warrants the accuracy, adequacy or completeness of this information, or otherwise endorses it in any way. Except where contrary to law, Westpac Group intend by this notice to exclude liability for this information. This information is subject to change without notice and none of Westpac or its related entities is under any obligation to update this information or correct any inaccuracy which may become apparent at a later date. This information may contain or incorporate by reference forward-looking statements. The words “believe”, “anticipate”, “expect”, “intend”, “plan”, “predict”, “continue”, “assume”, “positioned”, “may”, “will”, “should”, “shall”, “risk” and other similar expressions that are predictions of or indicate future events and future trends identify forward-looking statements. These forward-looking statements include all matters that are not historical facts. Past performance is not a reliable indicator of future performance, nor are forecasts of future performance. Whilst every effort has been taken to ensure that the assumptions on which any forecasts are based are reasonable, the forecasts may be affected by incorrect assumptions or by known or unknown risks and uncertainties. The ultimate outcomes may differ substantially from any forecasts.
Conflicts of Interest: In the normal course of offering banking products and services to its clients, the Westpac Group may act in several capacities (including issuer, market maker, underwriter, distributor, swap counterparty and calculation agent) simultaneously with respect to a financial instrument, giving rise to potential conflicts of interest which may impact the performance of a financial instrument. The Westpac Group may at any time transact or hold a position (including hedging and trading positions) for its own account or the account of a client in any financial instrument which may impact the performance of that financial instrument.
Author(s) disclaimer and declaration: The author(s) confirms that (a) no part of his/her compensation was, is, or will be, directly or indirectly, related to any views or (if applicable) recommendations expressed in this material; (b) this material accurately reflects his/her personal views about the financial products, companies or issuers (if applicable) and is based on sources reasonably believed to be reliable and accurate; (c) to the best of the author’s knowledge, they are not in receipt of inside information and this material does not contain inside information; and (d) no other part of the Westpac Group has made any attempt to influence this material.
Further important information regarding sustainability-related content: This material may contain statements relating to environmental, social and governance (ESG) topics. These are subject to known and unknown risks, and there are significant uncertainties, limitations, risks and assumptions in the metrics, modelling, data, scenarios, reporting and analysis on which the statements rely. In particular, these areas are rapidly evolving and maturing, and there are variations in approaches and common standards and practice, as well as uncertainty around future related policy and legislation. Some material may include information derived from publicly available sources that have not been independently verified. No representation or warranty is made as to the accuracy, completeness or reliability of the information. There is a risk that the analysis, estimates, judgements, assumptions, views, models, scenarios or projections used may turn out to be incorrect. These risks may cause actual outcomes to differ materially from those expressed or implied. The ESG-related statements in this material do not constitute advice, nor are they guarantees or predictions of future performance, and Westpac gives no representation, warranty or assurance (including as to the quality, accuracy or completeness of the statements). You should seek your own independent advice.
Additional country disclosures:
Australia: Westpac holds an Australian Financial Services Licence (No. 233714). You can access Westpac’s Financial Services Guide here or request a copy from your Westpac point of contact. To the extent that this information contains any general advice, it has been prepared without taking into account your objectives, financial situation or needs and before acting on it you should consider the appropriateness of the advice.
New Zealand: In New Zealand, Westpac Institutional Bank refers to the brand under which products and services are provided by either Westpac (NZ division) or Westpac New Zealand Limited (company number 1763882), the New Zealand incorporated subsidiary of Westpac ("WNZL"). Any product or service made available by WNZL does not represent an offer from Westpac or any of its subsidiaries (other than WNZL). Neither Westpac nor its other subsidiaries guarantee or otherwise support the performance of WNZL in respect of any such product. WNZL is not an authorised deposit-taking institution for the purposes of Australian prudential standards. The current disclosure statements for the New Zealand branch of Westpac and WNZL can be obtained at the internet address www.westpac.co.nz.
Singapore: This material has been prepared and issued for distribution in Singapore to institutional investors, accredited investors and expert investors (as defined in the applicable Singapore laws and regulations) only. Recipients of this material in Singapore should contact Westpac Singapore Branch in respect of any matters arising from, or in connection with, this material. Westpac Singapore Branch holds a wholesale banking licence and is subject to supervision by the Monetary Authority of Singapore.
Fiji: Unless otherwise specified, the products and services for Westpac Fiji are available from www.westpac.com.fj © Westpac Banking Corporation ABN 33 007 457 141. This information does not take your personal circumstances into account and before acting on it you should consider the appropriateness of the information for your financial situation. Westpac Banking Corporation ABN 33 007 457 141 is incorporated in NSW Australia and registered as a branch in Fiji. The liability of its members is limited.
Papua New Guinea: Unless otherwise specified, the products and services for Westpac PNG are available from www.westpac.com.pg © Westpac Banking Corporation ABN 33 007 457 141. This information does not take your personal circumstances into account and before acting on it you should consider the appropriateness of the information for your financial situation. Westpac Banking Corporation ABN 33 007 457 141 is incorporated in NSW Australia. Westpac is represented in Papua New Guinea by Westpac Bank - PNG - Limited. The liability of its members is limited.
U.S.: Westpac operates in the United States of America as a federally licensed branch, regulated by the Office of the Comptroller of the Currency. Westpac is also registered with the US Commodity Futures Trading Commission (“CFTC”) as a Swap Dealer, but is neither registered as, or affiliated with, a Futures Commission Merchant registered with the US CFTC. The services and products referenced above are not insured by the Federal Deposit Insurance Corporation (“FDIC”). Westpac Capital Markets, LLC (‘WCM’), a wholly-owned subsidiary of Westpac, is a broker-dealer registered under the U.S. Securities Exchange Act of 1934 (‘the Exchange Act’) and member of the Financial Industry Regulatory Authority (‘FINRA’). In accordance with APRA's Prudential Standard 222 'Association with Related Entities', Westpac does not stand behind WCM other than as provided for in certain legal agreements between Westpac and WCM and obligations of WCM do not represent liabilities of Westpac.
This communication is provided for distribution to U.S. institutional investors in reliance on the exemption from registration provided by Rule 15a-6 under the Exchange Act and is not subject to all of the independence and disclosure standards applicable to debt research reports prepared for retail investors in the United States. WCM is the U.S. distributor of this communication and accepts responsibility for the contents of this communication. Transactions by U.S. customers of any securities referenced herein should be effected through WCM. All disclaimers set out with respect to Westpac apply equally to WCM. If you would like to speak to someone regarding any security mentioned herein, please contact WCM on +1 212 389 1269. Investing in any non-U.S. securities or related financial instruments mentioned in this communication may present certain risks. The securities of non-U.S. issuers may not be registered with, or be subject to the regulations of, the SEC in the United States. Information on such non-U.S. securities or related financial instruments may be limited. Non-U.S. companies may not be subject to audit and reporting standards and regulatory requirements comparable to those in effect in the United States. The value of any investment or income from any securities or related derivative instruments denominated in a currency other than U.S. dollars is subject to exchange rate fluctuations that may have a positive or adverse effect on the value of or income from such securities or related derivative instruments.
The author of this communication is employed by Westpac and is not registered or qualified as a research analyst, representative, or associated person of WCM or any other U.S. broker-dealer under the rules of FINRA, any other U.S. self-regulatory organisation, or the laws, rules or regulations of any State. Unless otherwise specifically stated, the views expressed herein are solely those of the author and may differ from the information, views or analysis expressed by Westpac and/or its affiliates.
UK: The London branch of Westpac is authorised in the United Kingdom by the Prudential Regulation Authority (PRA) and is subject to regulation by the Financial Conduct Authority (FCA) and limited regulation by the PRA (Financial Services Register number: 124586). The London branch of Westpac is registered at Companies House as a branch established in the United Kingdom (Branch No. BR000106). Details about the extent of the regulation of Westpac’s London branch by the PRA are available from us on request.
This communication is not being made to or distributed to, and must not be passed on to, the general public in the United Kingdom. Rather, this communication is being made only to and is directed at (a) those persons falling within the definition of Investment Professionals (set out in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 (the “Order”)); (b) those persons falling within the definition of high net worth companies, unincorporated associations etc. (set out in Article 49(2)of the Order; (c) other persons to whom it may lawfully be communicated in accordance with the Order or (d) any persons to whom it may otherwise lawfully be made (all such persons together being referred to as “relevant persons”). Any person who is not a relevant person should not act or rely on this communication or any of its contents. In the same way, the information contained in this communication is intended for “eligible counterparties” and “professional clients” as defined by the rules of the Financial Conduct Authority and is not intended for “retail clients”. Westpac expressly prohibits you from passing on the information in this communication to any third party.
European Economic Area (“EEA”): This material may be distributed to you by either: (i) Westpac directly, or (ii) Westpac Europe GmbH (“WEG”) under a sub-licensing arrangement. WEG has not edited or otherwise modified the content of this material. WEG is authorised in Germany by the Federal Financial Supervision Authority (‘BaFin’) and subject to its regulation. WEG’s supervisory authorities are BaFin and the German Federal Bank (‘Deutsche Bundesbank’). WEG is registered with the commercial register (‘Handelsregister’) of the local court of Frankfurt am Main under registration number HRB 118483. In accordance with APRA’s Prudential Standard 222 ‘Association with Related Entities’, Westpac does not stand behind WEG other than as provided for in certain legal agreements (a risk transfer, sub-participation and collateral agreement) between Westpac and WEG and obligations of WEG do not represent liabilities of Westpac. Any product or service made available by WEG does not represent an offer from Westpac or any of its subsidiaries (other than WEG). All disclaimers set out with respect to Westpac apply equally to WEG.
This communication is not intended for distribution to, or use by any person or entity in any jurisdiction or country where such distribution or use would be contrary to local law or regulation.
This communication contains general commentary, research, and market colour. The communication does not constitute investment advice. The material may contain an ‘investment recommendation’ and/or ‘information recommending or suggesting an investment’, both as defined in Regulation (EU) No 596/2014 (including as applicable in the United Kingdom) (“MAR”). In accordance with the relevant provisions of MAR, reasonable care has been taken to ensure that the material has been objectively presented and that interests or conflicts of interest of the sender concerning the financial instruments to which that information relates have been disclosed.
Investment recommendations must be read alongside the specific disclosure which accompanies them and the general disclosure which can be found here. Such disclosure fulfils certain additional information requirements of MAR and associated delegated legislation and by accepting this communication you acknowledge that you are aware of the existence of such additional disclosure and its contents.
To the extent this communication comprises an investment recommendation it is classified as non-independent research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and therefore constitutes a marketing communication. Further, this communication is not subject to any prohibition on dealing ahead of the dissemination of investment research.