Commodities Update October 2026
Most commodities rose in September, with our broadest commodities index increasing 5.6%mth as persistent supply constraints and geopolitical tensions continued to drive markets. Coking coal led the gains (+22.3%mth), followed by Japanese LNG (+15.2%mth), Brent (+14.9%mth) and thermal coal (+11.7%mth). Copper (+1.3%mth), aluminium (+1.0%mth) and iron ore (+0.7%mth) also edged higher, while gold (-2.1%mth) and lithium (spodumene) (-4.8%mth) moved lower.
The following is based on text from the October Market Outlook (PDF 3MB)
For more details of our longer-term forecasts see October Commodity Forecasts
Most commodities rose in September, with many of the themes that drove moves across August remaining in place. Our broadest commodities index increased 5.6%mth, led by coking coal, which rose 22.3% on ongoing supply tightness following the Shanxi mine explosion. Japanese LNG (+15.2%mth) and Brent oil (+14.9%mth) also recorded strong gains amid persistent Middle East tensions, while thermal coal rose 11.7%mth. Copper (+1.3%mth) and aluminium (+1.0%mth) extended their recent gains, while iron ore managed a meagre advance (+0.7%mth), supported by higher freight and production costs. Gold fell 2.1%mth following the Fed’s September rate hike, while lithium was the weakest performer, with spodumene prices down 4.8%mth amid renewed oversupply concerns.
Oil rises, but product markets remain the key risk
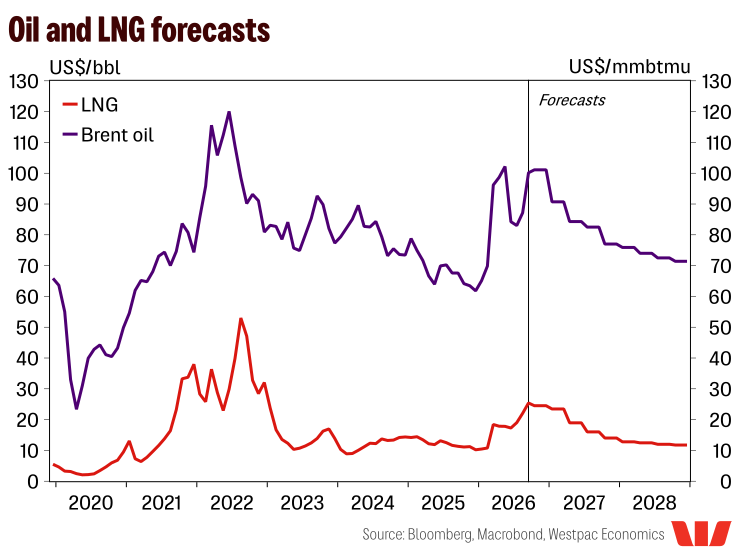
Brent crude rose 14.9%mth in September to average US$100.2/bbl on fading confidence in a lasting US-Iran agreement and intermittent attacks on shipping. Buffers remain depleted, with the IEA estimating global observed inventories were 507mb lower at the end of August than at the start of the conflict. This comes despite reported crude exports through the Strait of Hormuz recovering to around 70% to 90% of pre-conflict levels in late September. Saudi and UAE exports through the Yanbu and Fujairah pipelines continue, with the East-West pipeline back to normal after the early September attacks. Tanker crossings have risen, although transponders remain switched off, leaving visible transit at 1% to 4% of pre-conflict levels, while cargo transfers in the Gulf of Oman have increased as an alternative route. Fewer ships are also available, with many redeployed to other markets. Higher insurance premiums are adding to costs, with Gulf-to-China tanker rates above US$0.9mn a day, around 15x higher than a year ago. With prompt barrels (available for physical delivery) scarce, the gap between physical and futures prices widened again, with Dated Brent around US$136/bbl in early October against US$101/bbl for front-month futures.
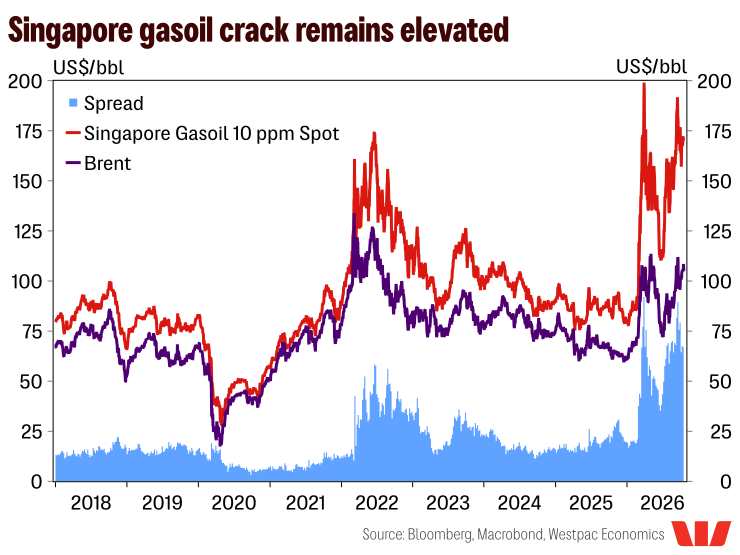
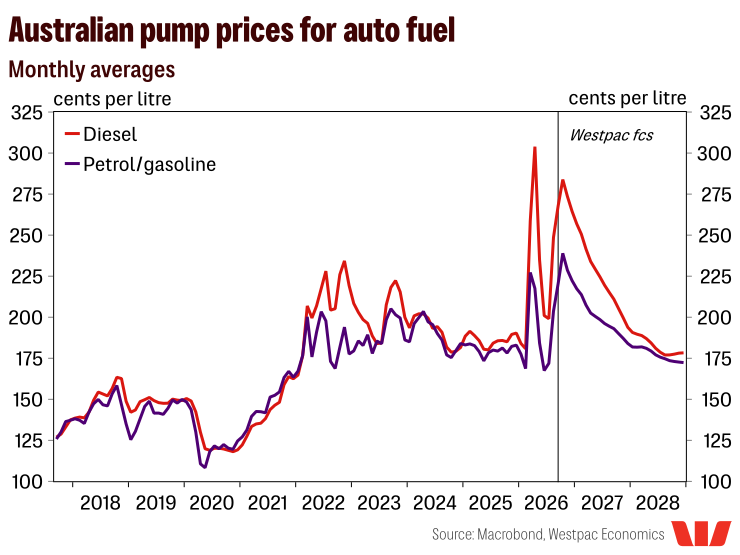
Refined product markets were already tight going into the conflict. Reduced Gulf supply, exacerbated by Ukrainian strikes on Russian refineries, has added to that tightness. Together with higher shipping costs and rising Dated Brent prices, Singapore Gasoil 10ppm (diesel) has roughly doubled since the Strait closed, compared with around 40% for crude futures. Consequently, Singapore gasoil crack spread widened to an average of around US$36.1/bbl in early October, from US$17.5/bbl across 2025. Alongside the Australian government’s excise tax returning to normal, after it had been halved, this lifted national diesel and petrol prices to around A$2.83/L and A$2.41/L.
We do not see a lasting US-Iran agreement until at least mid-2027. In the meantime, we assume there will not be a return to full-scale military intervention. However, periodic Iranian attacks on ships and facilities are expected to continue, as will the US blockade of Iranian exports, keeping a supply risk premium in place. We look for Brent futures to average around US$101/bbl in Q4, then ease gradually as demand from refiners and governments to rebuild stocks partly offsets recovering supply. As the premium fades and the market moves into surplus in late 2027, we forecast Brent at around US$77/bbl in Q4 2027, easing towards US$70/bbl in 2028 as Middle East production fully recovers.
Refined product supply is expected to recover more slowly than crude, with Gulf refinery runs not returning to pre-war levels until at least late 2027. Outside the Gulf, there has been some constructive news. The US has lifted sanctions on Russian diesel until April 2027, with Russia saying it will supply more than 4Mt over the coming months, while China has lifted its ban on refined product exports. However, we are cautious about how much this will add to the market in the short term. Much of the Russian supply is headed to the US and will depend on Russia’s ability to restore refining and export capacity, while the Russia-Ukraine energy ceasefire announced by President Trump does not appear to have any traction. China still manages exports through quotas, which are likely to increase only gradually as domestic stocks are rebuilt. Refinery runs should lift ahead of Lunar New Year, but any increase in exports will take time to reach regional markets. For additional analysis, including scenarios for both further escalation and an early resolution, see here.
LNG markets remain tight
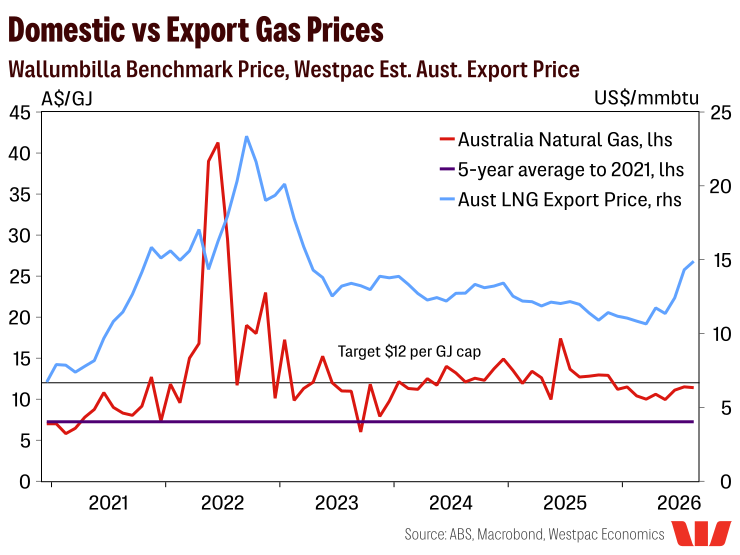
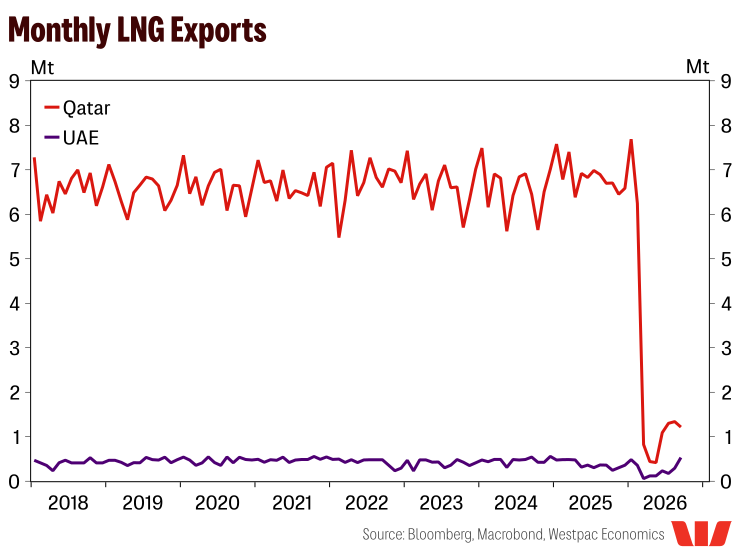
LNG prices continued to climb through September. Damage to the world's largest LNG export complex at Ras Laffan in Qatar and the inability to divert flows around the Strait of Hormuz continue to weigh on supply. These constraints have been compounded by stronger competition between Northeast Asia and Europe for flexible Atlantic Basin cargoes ahead of winter, as European gas storage remains below seasonal norms. As a result, Japanese LNG prices rose 15.2%mth in September, with average prices reaching US$25.4/mmbtu. While this is more than double pre-conflict levels, the pace of price gains is being somewhat tempered by demand destruction across Asia.
We have raised our forecast for Japanese LNG prices in the December quarter to US$24.5/mmbtu. Supply recovery is expected to remain constrained, with prices unlikely to return to pre-conflict levels until 2028. While uncertainty over the balance between current supply disruptions and future oversupply is complicating negotiations over long-term LNG contract prices, Australia is well positioned to capture a reliability premium as buyers place greater value on secure supply. Domestically, the Australian gas market remains relatively insulated, supported by the FY2027 Federal Budget's domestic gas reservation scheme, which requires exporters to supply the equivalent of up to 20% of gas exports to the Australian market. The government's objective remains to cap domestic gas prices at around $12/GJ.
India increasingly the swing factor for coal
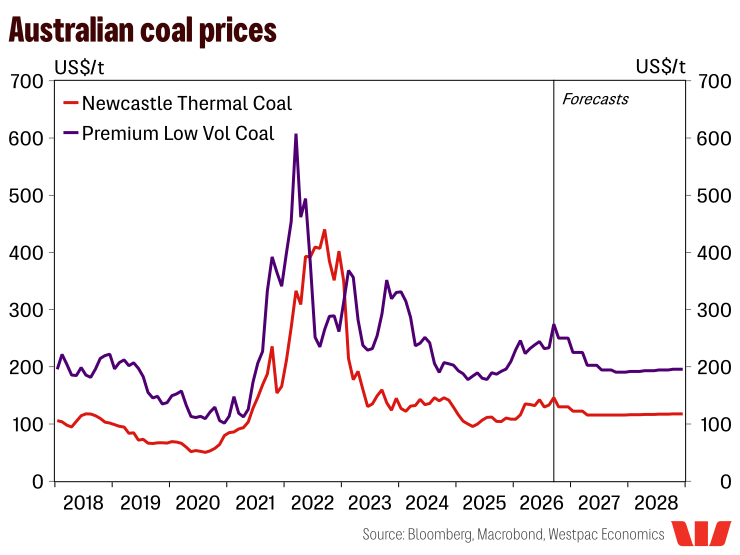
Newcastle thermal coal prices rose 11.7%mth in September, averaging US$146/t over the month, the highest monthly average since September 2023. Key sources of support remain in place, keeping prices well above pre-conflict levels. LNG markets continue to underpin the relative cost competitiveness of thermal coal, while shifting energy security priorities across Japan, South Korea and Taiwan have encouraged greater coal procurement as a hedge against LNG supply disruption. China also emerged as a stronger seaborne buyer, reflecting tighter domestic supply following the Shanxi mining disaster. India has provided a further source of demand. El Niño has brought hotter conditions and a weaker monsoon season, simultaneously lifting electricity demand and weighing heavily on hydro generation. The resulting squeeze saw up to 40% of Indian coal-fired power plants reportedly running critically low on fuel in late September.
Against this backdrop, we now expect Newcastle thermal coal to average US$130/t in the December quarter before easing towards US$116/t through 2027 as global energy prices recede. Over the longer term, prices are expected to rise as demand outpaces supply growth, with mine depletion, regulatory hurdles, community opposition and financing constraints limiting new capacity, particularly in Australia.
Queensland premium low-vol coking coal prices led gains across the commodities complex in September, rising 22.3%mth to average US$275.8/t. The increase reflects strong Chinese demand, with buying accelerating ahead of the peak steelmaking season. This has been compounded by domestic supply shortages following the gas explosion at a Shanxi coking coal mine in May, which prompted production suspensions and safety inspections. These restrictions have proven more persistent than initially expected, compounded by broader anti-corruption campaigns. While tightness stemming from the Shanxi accident is expected to begin unwinding through Q4, a full return of curtailed supply is not anticipated until H1 2027. The resulting supply loss was initially expected to be offset by increased Mongolian imports, but diesel shortages have constrained local coal production. Mongolia sources much of its diesel from Russia, where disruptions are likely to persist for some time, prompting China to return to the seaborne market and benefiting Australian exporters.
Looking ahead, the normalisation of Mongolian exports and weaker Chinese steelmaker margins are expected to weigh on seaborne demand. India should provide some offset as the country emerges from the monsoon season and steel production lifts, although comfortable port inventories and margin pressure from elevated input costs should limit the strength of this demand impulse. As a result, we forecast premium low-vol coking coal prices to remain elevated in the December quarter, averaging US$250/t, before moderating as Chinese buying subsides following Lunar New Year. Prices are expected to ease further through 2027 alongside the long-term decline in Chinese steel production and increased use of electric arc furnaces, while rising Indian import requirements, supported by steel capacity expansion and urbanisation, should provide a floor.
Cost pressures place a floor under iron ore prices
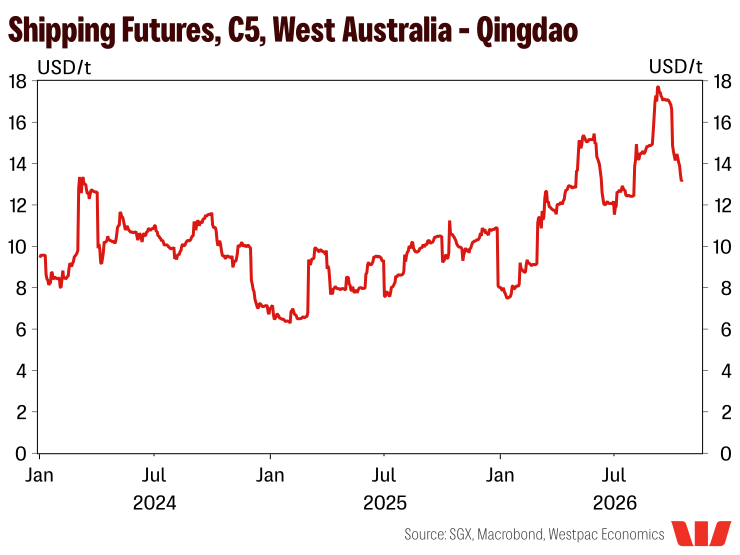
Iron ore prices (62% Fe index) rose 0.7%mth in September to average US$98.3/t. The increase largely reflects elevated freight and energy costs. Shipping futures from Western Australia to Qingdao continued to rise, with the September monthly average reaching its highest level since the start of the Middle East conflict and sitting 91% above the 2025 average. With freight accounting for an estimated 15–30% of delivered costs, and capesize rates remaining elevated despite easing from recent highs, some price support is likely to persist. Higher costs are becoming increasingly evident across producer cost curves. Wood Mackenzie estimates the 90th percentile cost of production at US$79.8/t, 5.7% above 2025 levels, while more than 5% of global supply is estimated to be operating below break-even at current prices. With costs expected to remain elevated through 2027, the higher industry cost base should help limit downside despite the broader headwinds facing the sector. Robust Chinese steel exports, which remained above 10Mt for a fifth consecutive month in September, are providing some additional support.
That said, the major headwinds facing iron ore remain firmly in place. Seaborne supply continues to expand across Australia and Brazil, alongside the ramp-up of Simandou in Guinea. At the same time, the Shanxi mining disaster has kept coking coal markets particularly tight, further compressing steelmaker margins already under pressure from intense competition between mills and weighing particularly on demand for lower-grade ores. China's domestic economy also presents limited upside, with urban fixed asset investment down 7.2%ytd in September, while iron ore inventories at Chinese ports remain historically elevated. We expect the 62% Fe index to average US$95/t in the December quarter, with the higher industry cost base helping offset some of these headwinds. Additional uncertainty stems from the larger-than-usual El Niño event, with above-average rainfall across southern and eastern China posing further downside risk through potential disruption to construction activity.
The medium-term outlook remains increasingly challenging, with surplus conditions expected to emerge. Supply-side pressures are building as new low-cost output from Simandou enters the market, with Wood Mackenzie estimating export volumes could double to 40Mt in 2027. Persistently high inventories in China and softer global steel demand, as major economies contend with elevated energy costs, are expected to place further downward pressure on prices. Increased scrap usage and the structural decline in Chinese steel production are also eroding underlying demand, with growth in India and South-East Asia, supported by urbanisation and population growth, providing only a partial offset. We therefore expect iron ore prices to soften further, averaging around US$83/t in the December quarter of 2027 as surplus conditions become more evident. Beyond this, lower prices and increasing competition from higher-grade African and Brazilian supply are likely to weigh on Australia's iron ore export earnings.
Gold caught between higher yields and safe-haven demand
Gold fell 2.1%mth in September as US Treasury yields continued to rise through the month. A key catalyst was the FOMC's 25bp rate hike in mid-September, alongside expectations of further tightening later in the year. As a non-yielding asset, gold has faced broader pressure throughout the conflict as markets weighed the inflationary implications of elevated energy prices and the prospect of further central bank tightening. Despite this, the broader backdrop remains supportive. Gold has recently benefited from safe-haven demand amid a broad mix of macroeconomic and geopolitical risks, alongside volatility associated with the AI trade. This resilience is evident in investment flows, with Word Gold Council reporting global gold ETFs attracting US$31bn in Q3 2026, the strongest quarter on record. Further support continues to come from central bank buying, while safe-haven demand may strengthen around the US midterm elections.
We therefore expect modest gains through the remainder of 2026, with a December quarter average of US$4,350/oz. From there, we expect a period of consolidation through 2027 as brownfield expansions at existing operations lift supply in response to recent high prices, while an elevated Fed funds rate limits upside for non-yielding assets. Over the longer term, structural support should persist despite continued financial-market volatility. Growing Asian participation in gold trading, investment and physical distribution should broaden the investor base, while US fiscal and currency concerns, central bank buying and reserve diversification provide additional support.
Tariff disruption eases for copper
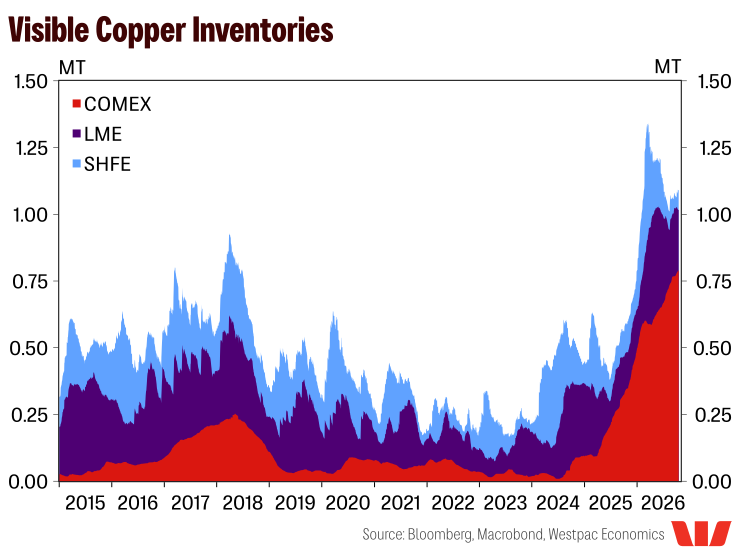
LME copper prices posted more modest gains in September, rising 1.3%mth to average US$14,490/t. While prices briefly reached a new high during the month, overall gains were tempered by an easing in tariff-related disruption. Reports in early September that the US Government's decision on Section 232 tariff implementation had stalled sent prices sharply lower, amid concerns in Washington that higher copper prices could add to manufacturing costs in an already elevated cost environment. Accordingly, the pace of COMEX inventory accumulation slowed to 4.4%mth, down from the stronger gains recorded in July and August. Nevertheless, the continued pull of material into the US has contributed to physical tightness elsewhere, with LME backwardation between prompt and three-month delivery easing but remaining elevated through September. More meaningful support came from supply disruptions in Chile, which accounts for roughly a quarter of global copper production. Weather disruptions, the death of a worker halting operations at the world's largest copper mine, declining ore grades and ageing assets have all contributed to a weaker production outlook for the remainder of 2026.
Prices have so far struggled to gain further traction through October. A key headwind has been the broader sell-off in the AI trade across equity markets, with copper's exposure to AI-related investment making it vulnerable to the shift in sentiment. The historically elevated copper-to-aluminium price ratio also presents a near-term headwind, increasing the incentive for substitution where feasible. That said, while copper's near-term price path remains heavily dependent on forthcoming tariff announcements, we expect prices to remain elevated through the remainder of 2026. Ongoing electrification following the latest energy shock, together with robust AI and data-centre investment, should continue to underpin demand, while cautious COMEX inventory accumulation is also likely to persist. Against this backdrop, we expect LME copper to average US$14,750/t in Q4.
The medium-term outlook is likely to become more challenging. While the eventual outcome of the Section 232 review is expected to weigh on prices, a softer demand impulse appears more likely than a large release of US inventories, with accumulated stocks likely to be consumed domestically. China's property sector also remains under pressure, with fixed asset investment falling 7.2%ytd in September, representing an important source of lost demand, while incremental mine supply expansion should place further downward pressure on the market. However, structural electrification trends and manufacturing localisation should provide a floor under prices, with a trough of around US$12,760/t expected by early 2029. Beyond this point, prices are expected to strengthen considerably as net-zero targets approach, EV uptake gathers momentum, renewable deployment accelerates and expanding data-centre investment drives additional demand for energy generation and transmission infrastructure. For Australia, this structural rise in copper demand and prices should also support a gradual diversification of the export mix away from exposure to Chinese steel cycles.
Gulf disruptions continue to support aluminium
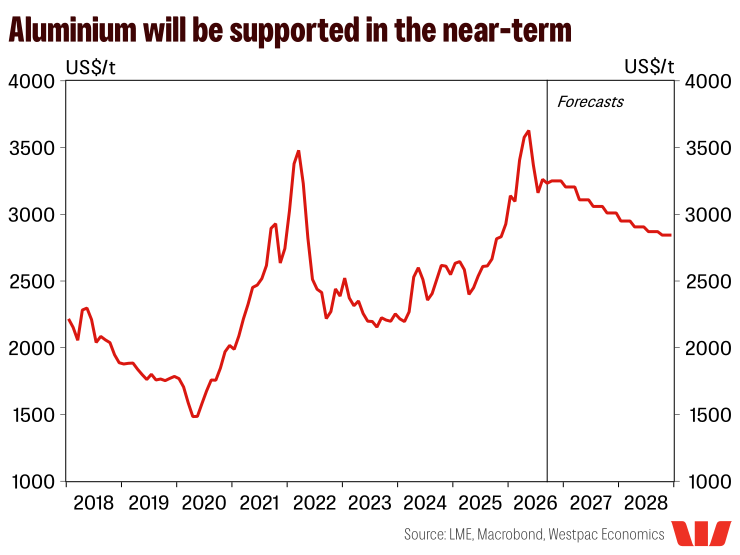
LME Aluminium prices rose 1.0%mth in September, averaging US$3,284/t. Continued disruption to Gulf smelting capacity has maintained upward pressure on the market, with the region accounting for around 9% of global smelting capacity and a considerably larger share of global trade. While limited volumes of metal are beginning to emerge from the Middle East, delivery times remain extended and difficulties securing sufficient alumina feedstock continue to constrain production. As a result, IAI statistics indicate Gulf states’ (GCC) production in August remained 42.6% below August 2025 levels. Given the time- and capital-intensive nature of restarting Gulf smelting capacity, we expect market tightness to persist through the remainder of 2026. Emirates Global Aluminium (EGA) has indicated its Al Taweelah site remains on track for a full restart only by Q1 2027, while Alba in Bahrain continues to operate below capacity. China is unlikely to fully offset these losses, with aluminium output increasing by just 3.1%yr in August, replacing only around half of lost GCC production. Further growth is constrained by high utilisation rates and China's capacity replacement policy, which restricts new production unless matched by the permanent closure of approved existing capacity. Elevated energy prices should also provide some support, given the electricity-intensive nature of aluminium smelting and the risk that higher-cost capacity becomes uneconomic.
Alumina markets are adding to these pressures. Prices have risen above US$380/t at the start of October, reflecting elevated freight costs and production cuts at key suppliers. Alcoa has lowered its 2026 alumina production guidance by 200–300kt following operational disruptions at one of its Western Australian refineries, while Alunorte has reduced output by 100–120kt following earlier disruptions to gas supply.
Against this backdrop, we expect aluminium prices to remain supported through the remainder of 2026, although we do not anticipate a full return of the war premium. Higher prices are incentivising capacity restarts across Western economies and South-East Asia, while Chinese demand for aluminium remains subdued. We therefore forecast prices to average US$3,250/t in the December quarter. Thereafter, prices are expected to ease as Gulf production recovers and new Indonesian smelting capacity backed by Chinese investment comes online. Longer-term support should come from EV, grid infrastructure and data-centre investment, although growing competition for power from data centres may constrain future smelting capacity expansion.
Chinese policy fuels lithium oversupply fears
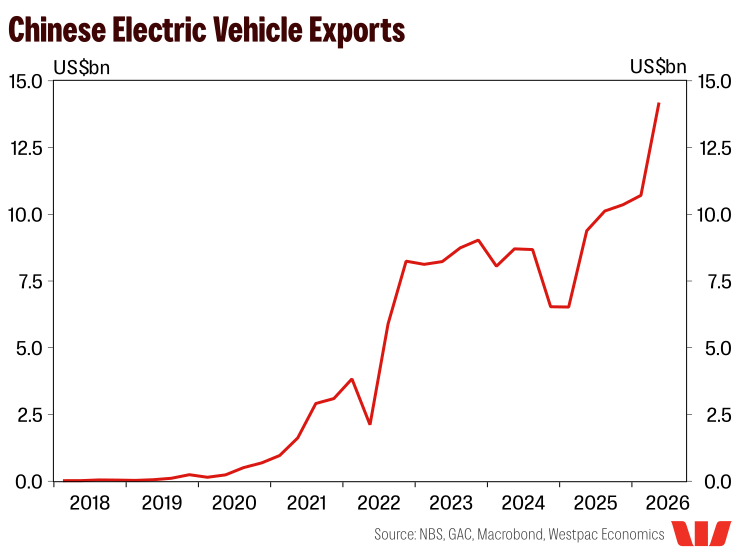
Markets were spooked by renewed lithium oversupply concerns in September after China's Ministry of Industry and Information Technology froze approvals for greenfield power and battery energy storage system (BESS) factories that had yet to break ground. The move reflects growing concerns around excess capacity in the energy storage sector and forms part of Beijing's broader anti-involution agenda. Sentiment was further weighed down by the potential restart of CATL's Jianxiawo mine, which accounts for around 3–4% of global lithium supply at full capacity and remains suspended pending environmental approvals. As a result, spodumene (6% FOB Australia) prices fell 4.8%mth in September to US$2,007/t, with ongoing BESS and EV demand insufficient to offset oversupply concerns. Despite this, the near-term outlook remains constructive. Lean downstream inventories and continued investment in energy storage following the recent energy shock should support demand, alongside accelerating EV adoption. The IEA projects electric vehicles will account for 28% of global vehicle sales in 2026, while lower-cost Chinese EVs continue to gain market share, having accounted for 60% of global EV sales in 2025.
Over the medium to longer term, however, additional supply, particularly from Australia, is expected to weigh on prices. Recent tax changes in China, which impose a consumption tax on lithium-ion batteries while exempting sodium-ion and solid-state batteries until end-2028, may also encourage some substitution away from lithium at the margin. Nevertheless, lithium is expected to remain the dominant battery chemistry, with demand underpinned by structural electrification trends. EVs will remain the primary source of demand, while BESS growth should accelerate alongside renewable generation and rising data-centre power requirements.
Lithium is also becoming increasingly strategically important as Western economies seek to diversify critical mineral supply chains. The Trump Administration's recent US$3bn investment package for critical minerals and battery projects underscores this shift. Australia is well positioned to benefit as a key supplier of lithium feedstock and battery materials, although expanding domestic production means the gains are likely to come through higher export volumes rather than materially higher prices.
Stay informed with Westpac IQ
Get the latest reports straight to your inbox.
Related articles
Commodities Update September 2026
Commodities Update August 2026
Commodities Update July 2026
Browse topics
Disclaimer
©2026 Westpac Banking Corporation ABN 33 007 457 141 (including where acting under any of its Westpac, St George, Bank of Melbourne or BankSA brands, collectively, “Westpac”). References to the “Westpac Group” are to Westpac and its subsidiaries and includes the directors, employees and representatives of Westpac and its subsidiaries.
Things you should know
We respect your privacy: You can view the New Zealand Privacy Policy here, or the Australian Group Privacy Statement here. Each time someone visits our site, data is captured so that we can accurately evaluate the quality of our content and make improvements for you. We may at times use technology to capture data about you to help us to better understand you and your needs, including potentially for the purposes of assessing your individual reading habits and interests to allow us to provide suggestions regarding other reading material which may be suitable for you.
This information, unless specifically indicated otherwise, is under copyright of the Westpac Group. None of the material, nor its contents, nor any copy of it, may be altered in any way, transmitted to, copied of distributed to any other party without the prior written permission of the Westpac Group.
Disclaimer
This information has been prepared by Westpac and is intended for information purposes only. It is not intended to reflect any recommendation or financial advice and investment decisions should not be based on it. This information does not constitute an offer, a solicitation of an offer, or an inducement to subscribe for, purchase or sell any financial instrument or to enter into a legally binding contract. To the extent that this information contains any general advice, it has been prepared without taking into account your objectives, financial situation or needs and before acting on it you should consider the appropriateness of the advice. Certain types of transactions, including those involving futures, options and high yield securities give rise to substantial risk and are not suitable for all investors. We recommend that you seek your own independent legal or financial advice before proceeding with any investment decision.
This information may contain material provided by third parties. While such material is published with the necessary permission none of Westpac or its related entities accepts any responsibility for the accuracy or completeness of any such material. Although we have made every effort to ensure this information is free from error, none of Westpac or its related entities warrants the accuracy, adequacy or completeness of this information, or otherwise endorses it in any way. Except where contrary to law, Westpac Group intend by this notice to exclude liability for this information. This information is subject to change without notice and none of Westpac or its related entities is under any obligation to update this information or correct any inaccuracy which may become apparent at a later date. This information may contain or incorporate by reference forward-looking statements. The words “believe”, “anticipate”, “expect”, “intend”, “plan”, “predict”, “continue”, “assume”, “positioned”, “may”, “will”, “should”, “shall”, “risk” and other similar expressions that are predictions of or indicate future events and future trends identify forward-looking statements. These forward-looking statements include all matters that are not historical facts. Past performance is not a reliable indicator of future performance, nor are forecasts of future performance. Whilst every effort has been taken to ensure that the assumptions on which any forecasts are based are reasonable, the forecasts may be affected by incorrect assumptions or by known or unknown risks and uncertainties. The ultimate outcomes may differ substantially from any forecasts.
Conflicts of Interest: In the normal course of offering banking products and services to its clients, the Westpac Group may act in several capacities (including issuer, market maker, underwriter, distributor, swap counterparty and calculation agent) simultaneously with respect to a financial instrument, giving rise to potential conflicts of interest which may impact the performance of a financial instrument. The Westpac Group may at any time transact or hold a position (including hedging and trading positions) for its own account or the account of a client in any financial instrument which may impact the performance of that financial instrument.
Author(s) disclaimer and declaration: The author(s) confirms that (a) no part of his/her compensation was, is, or will be, directly or indirectly, related to any views or (if applicable) recommendations expressed in this material; (b) this material accurately reflects his/her personal views about the financial products, companies or issuers (if applicable) and is based on sources reasonably believed to be reliable and accurate; (c) to the best of the author’s knowledge, they are not in receipt of inside information and this material does not contain inside information; and (d) no other part of the Westpac Group has made any attempt to influence this material.
Further important information regarding sustainability-related content: This material may contain statements relating to environmental, social and governance (ESG) topics. These are subject to known and unknown risks, and there are significant uncertainties, limitations, risks and assumptions in the metrics, modelling, data, scenarios, reporting and analysis on which the statements rely. In particular, these areas are rapidly evolving and maturing, and there are variations in approaches and common standards and practice, as well as uncertainty around future related policy and legislation. Some material may include information derived from publicly available sources that have not been independently verified. No representation or warranty is made as to the accuracy, completeness or reliability of the information. There is a risk that the analysis, estimates, judgements, assumptions, views, models, scenarios or projections used may turn out to be incorrect. These risks may cause actual outcomes to differ materially from those expressed or implied. The ESG-related statements in this material do not constitute advice, nor are they guarantees or predictions of future performance, and Westpac gives no representation, warranty or assurance (including as to the quality, accuracy or completeness of the statements). You should seek your own independent advice.
Additional country disclosures:
Australia: Westpac holds an Australian Financial Services Licence (No. 233714). You can access Westpac’s Financial Services Guide here or request a copy from your Westpac point of contact. To the extent that this information contains any general advice, it has been prepared without taking into account your objectives, financial situation or needs and before acting on it you should consider the appropriateness of the advice.
New Zealand: In New Zealand, Westpac Institutional Bank refers to the brand under which products and services are provided by either Westpac (NZ division) or Westpac New Zealand Limited (company number 1763882), the New Zealand incorporated subsidiary of Westpac ("WNZL"). Any product or service made available by WNZL does not represent an offer from Westpac or any of its subsidiaries (other than WNZL). Neither Westpac nor its other subsidiaries guarantee or otherwise support the performance of WNZL in respect of any such product. WNZL is not an authorised deposit-taking institution for the purposes of Australian prudential standards. The current disclosure statements for the New Zealand branch of Westpac and WNZL can be obtained at the internet address www.westpac.co.nz.
Singapore: This material has been prepared and issued for distribution in Singapore to institutional investors, accredited investors and expert investors (as defined in the applicable Singapore laws and regulations) only. Recipients of this material in Singapore should contact Westpac Singapore Branch in respect of any matters arising from, or in connection with, this material. Westpac Singapore Branch holds a wholesale banking licence and is subject to supervision by the Monetary Authority of Singapore.
Fiji: Unless otherwise specified, the products and services for Westpac Fiji are available from www.westpac.com.fj © Westpac Banking Corporation ABN 33 007 457 141. This information does not take your personal circumstances into account and before acting on it you should consider the appropriateness of the information for your financial situation. Westpac Banking Corporation ABN 33 007 457 141 is incorporated in NSW Australia and registered as a branch in Fiji. The liability of its members is limited.
Papua New Guinea: Unless otherwise specified, the products and services for Westpac PNG are available from www.westpac.com.pg © Westpac Banking Corporation ABN 33 007 457 141. This information does not take your personal circumstances into account and before acting on it you should consider the appropriateness of the information for your financial situation. Westpac Banking Corporation ABN 33 007 457 141 is incorporated in NSW Australia. Westpac is represented in Papua New Guinea by Westpac Bank - PNG - Limited. The liability of its members is limited.
U.S.: Westpac operates in the United States of America as a federally licensed branch, regulated by the Office of the Comptroller of the Currency. Westpac is also registered with the US Commodity Futures Trading Commission (“CFTC”) as a Swap Dealer, but is neither registered as, or affiliated with, a Futures Commission Merchant registered with the US CFTC. The services and products referenced above are not insured by the Federal Deposit Insurance Corporation (“FDIC”). Westpac Capital Markets, LLC (‘WCM’), a wholly-owned subsidiary of Westpac, is a broker-dealer registered under the U.S. Securities Exchange Act of 1934 (‘the Exchange Act’) and member of the Financial Industry Regulatory Authority (‘FINRA’). In accordance with APRA's Prudential Standard 222 'Association with Related Entities', Westpac does not stand behind WCM other than as provided for in certain legal agreements between Westpac and WCM and obligations of WCM do not represent liabilities of Westpac.
This communication is provided for distribution to U.S. institutional investors in reliance on the exemption from registration provided by Rule 15a-6 under the Exchange Act and is not subject to all of the independence and disclosure standards applicable to debt research reports prepared for retail investors in the United States. WCM is the U.S. distributor of this communication and accepts responsibility for the contents of this communication. Transactions by U.S. customers of any securities referenced herein should be effected through WCM. All disclaimers set out with respect to Westpac apply equally to WCM. If you would like to speak to someone regarding any security mentioned herein, please contact WCM on +1 212 389 1269. Investing in any non-U.S. securities or related financial instruments mentioned in this communication may present certain risks. The securities of non-U.S. issuers may not be registered with, or be subject to the regulations of, the SEC in the United States. Information on such non-U.S. securities or related financial instruments may be limited. Non-U.S. companies may not be subject to audit and reporting standards and regulatory requirements comparable to those in effect in the United States. The value of any investment or income from any securities or related derivative instruments denominated in a currency other than U.S. dollars is subject to exchange rate fluctuations that may have a positive or adverse effect on the value of or income from such securities or related derivative instruments.
The author of this communication is employed by Westpac and is not registered or qualified as a research analyst, representative, or associated person of WCM or any other U.S. broker-dealer under the rules of FINRA, any other U.S. self-regulatory organisation, or the laws, rules or regulations of any State. Unless otherwise specifically stated, the views expressed herein are solely those of the author and may differ from the information, views or analysis expressed by Westpac and/or its affiliates.
UK: The London branch of Westpac is authorised in the United Kingdom by the Prudential Regulation Authority (PRA) and is subject to regulation by the Financial Conduct Authority (FCA) and limited regulation by the PRA (Financial Services Register number: 124586). The London branch of Westpac is registered at Companies House as a branch established in the United Kingdom (Branch No. BR000106). Details about the extent of the regulation of Westpac’s London branch by the PRA are available from us on request.
This communication is not being made to or distributed to, and must not be passed on to, the general public in the United Kingdom. Rather, this communication is being made only to and is directed at (a) those persons falling within the definition of Investment Professionals (set out in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 (the “Order”)); (b) those persons falling within the definition of high net worth companies, unincorporated associations etc. (set out in Article 49(2)of the Order; (c) other persons to whom it may lawfully be communicated in accordance with the Order or (d) any persons to whom it may otherwise lawfully be made (all such persons together being referred to as “relevant persons”). Any person who is not a relevant person should not act or rely on this communication or any of its contents. In the same way, the information contained in this communication is intended for “eligible counterparties” and “professional clients” as defined by the rules of the Financial Conduct Authority and is not intended for “retail clients”. Westpac expressly prohibits you from passing on the information in this communication to any third party.
European Economic Area (“EEA”): This material may be distributed to you by either: (i) Westpac directly, or (ii) Westpac Europe GmbH (“WEG”) under a sub-licensing arrangement. WEG has not edited or otherwise modified the content of this material. WEG is authorised in Germany by the Federal Financial Supervision Authority (‘BaFin’) and subject to its regulation. WEG’s supervisory authorities are BaFin and the German Federal Bank (‘Deutsche Bundesbank’). WEG is registered with the commercial register (‘Handelsregister’) of the local court of Frankfurt am Main under registration number HRB 118483. In accordance with APRA’s Prudential Standard 222 ‘Association with Related Entities’, Westpac does not stand behind WEG other than as provided for in certain legal agreements (a risk transfer, sub-participation and collateral agreement) between Westpac and WEG and obligations of WEG do not represent liabilities of Westpac. Any product or service made available by WEG does not represent an offer from Westpac or any of its subsidiaries (other than WEG). All disclaimers set out with respect to Westpac apply equally to WEG.
This communication is not intended for distribution to, or use by any person or entity in any jurisdiction or country where such distribution or use would be contrary to local law or regulation.
This communication contains general commentary, research, and market colour. The communication does not constitute investment advice. The material may contain an ‘investment recommendation’ and/or ‘information recommending or suggesting an investment’, both as defined in Regulation (EU) No 596/2014 (including as applicable in the United Kingdom) (“MAR”). In accordance with the relevant provisions of MAR, reasonable care has been taken to ensure that the material has been objectively presented and that interests or conflicts of interest of the sender concerning the financial instruments to which that information relates have been disclosed.
Investment recommendations must be read alongside the specific disclosure which accompanies them and the general disclosure which can be found here. Such disclosure fulfils certain additional information requirements of MAR and associated delegated legislation and by accepting this communication you acknowledge that you are aware of the existence of such additional disclosure and its contents.
To the extent this communication comprises an investment recommendation it is classified as non-independent research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and therefore constitutes a marketing communication. Further, this communication is not subject to any prohibition on dealing ahead of the dissemination of investment research.