Commodities Update November 2026
Our broadest commodities index increased 0.6%mth as sharp gains across energy offset weakness elsewhere. Japanese LNG led the gains (+12.8%mth), followed by Brent (+6.1%mth) and thermal coal (+2.9%mth). Copper was broadly unchanged (–0.1%mth), while coking coal (–3.5%mth), gold (–5.0%mth), iron ore (–6.1%mth) and aluminium (–6.5%mth) moved lower. Lithium was the clear underperformer, with spodumene down 26.1%mth.
The following is based on text from the November Market Outlook (PDF 3MB)
For more details of our longer-term forecasts see November Commodity Forecasts
The commodities complex was a story of two halves in October, with energy prices rising sharply while most other commodities weakened. Our broadest commodities index gained 0.7%mth, led by Japanese LNG (+12.8%mth), with Brent (+6.1%mth) and thermal coal (+2.9%mth) also higher amid energy-market disruption. Copper edged 0.1%mth lower as AI sentiment weakened, while coking coal (-3.5%mth) reversed recent gains and elevated yields continued to weigh on gold (-5.0%mth). Iron ore extended its slide (-6.1%mth), while aluminium fell 6.5%mth. Lithium was the clear underperformer, with spodumene down 26.1%mth after environmental approval for CATL’s Jianxiawo mine renewed oversupply concerns.
Oil supply returns, risk premium remains
Brent crude rose 6.1%mth in October to average US$106.2/bbl as ongoing infrastructure strikes and attacks on shipping through the Strait continued to weigh on supply. Inventory buffers are depleted, with the EIA estimating OECD inventories fell a further 33mb in September, leaving stocks 141mb below February pre-conflict levels. This comes despite reported crude exports from Gulf producers recovering to more than 85% of year-ago levels in October. Saudi and UAE exports through the Yanbu and Fujairah pipelines continue, while the East-West pipeline has returned to normal following the attacks in early September.
Tanker crossings have also increased aided by US fighter escorts, although transponders remain switched off, leaving visible transit at just 1% to 4% of pre-conflict levels. Cargo transfers in the Gulf of Oman have meanwhile increased as an alternative route. Supply from elsewhere has also responded, with October South and Central American seaborne crude exports around 44% higher than a year ago. Reflecting the improvement in supply, in early November Dated Brent was trading at a discount to the front-month futures contract. Optimism around recent US-Iran negotiations also weighed modestly on crude prices, with Tehran reportedly demonstrating some willingness to negotiate over its nuclear programme. The Republican defeat in the US midterms further saw markets price a less intense US campaign, with President Trump later conceding it was “largely true” that Republicans lost partly because of the war. Nonetheless, prices remain elevated, with geopolitical risk only part of the story. Fewer tankers remain available after vessels were redeployed to other markets leading to higher shipping rates, while higher insurance premiums also add to costs. Gulf-to-China tanker rates have eased but, at around US$0.3mn per day, they are still more than 4 times their 2025 average.
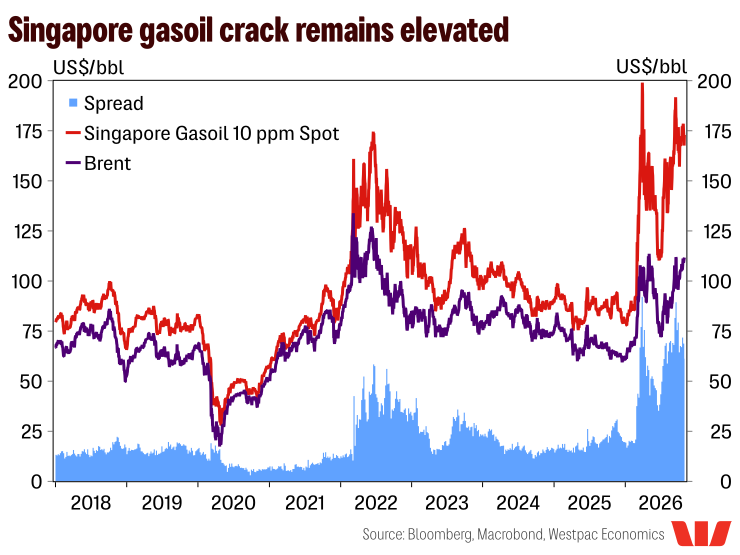
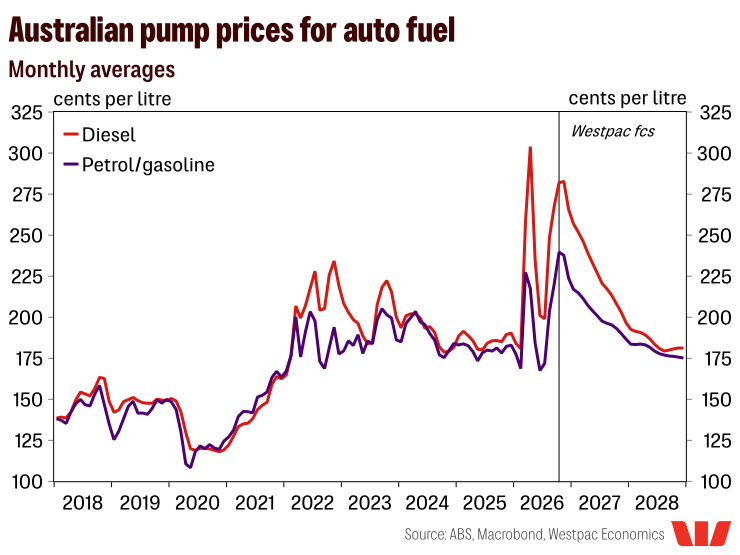
Refined product markets were already tight heading into the conflict. Reduced Gulf supply, compounded by Ukrainian strikes on Russian refineries, added to this pressure. Until recently, refineries also faced less optimal feedstocks following the loss of Middle Eastern crude. Together with higher shipping costs and elevated Dated Brent prices, Singapore Gasoil 10ppm roughly doubled since the Strait closed, compared with an increase of around 40% for crude futures. Although Dated Brent has softened in recent days, helping lower Singapore gasoil prices, refining margins remain exceptionally elevated. The gasoil crack spread averaged around US$60/bbl in the first half of November, compared with US$17.5/bbl across 2025. As a result, national diesel and petrol prices remain elevated at around A$2.71/L and A$2.23/L, respectively.
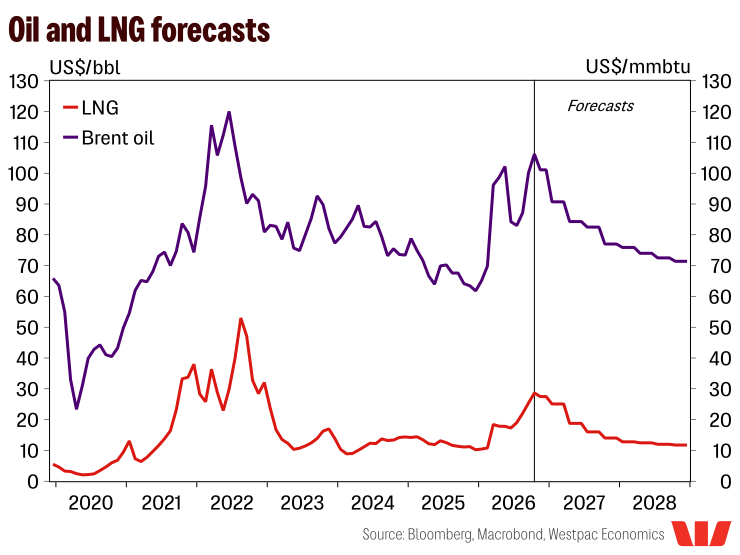
We do not expect a lasting US-Iran agreement until at least mid-2027. In the meantime, we assume there will not be a return to full-scale military intervention. However, periodic Iranian attacks on ships and facilities may continue, alongside the US blockade of Iranian exports, maintaining a supply risk premium. We expect Brent futures to average around US$101/bbl in Q4 before easing gradually as recovering supply is partly offset by demand from refiners and governments rebuilding inventories. As the risk premium fades and the market moves into surplus in late 2027, we forecast Brent at around US$77/bbl in Q4 2027. Prices are then expected to ease towards US$70/bbl in 2028 as Middle Eastern production fully recovers.
Refined product supply is expected to recover more slowly than crude, with Gulf refinery runs not returning to pre-war levels until at least late 2027. China also remains a subdued participant, accounting for around 17% of global seaborne crude imports in October, down from 19% a year earlier. This likely reflects the loss of cheaper Iranian crude, with independent Chinese refiners still operating at only around 60%. Refinery runs should lift ahead of Lunar New Year, although any resulting increase in product exports will take time to reach regional markets.
China remains a wild card for refined product supplies. China's crude inventories returned to growth in October as improving flows through the Strait of Hormuz lifted imports, while refinery demand remained subdued. Strong stock building earlier in the year means inventories remain ample despite draws since May. That leaves China well placed to lift refinery runs and refined-product exports if attractive margins provide the incentive.
For additional analysis, including scenarios for further escalation and an earlier resolution, see here.
Qatar's limited bypass options keep LNG market tight
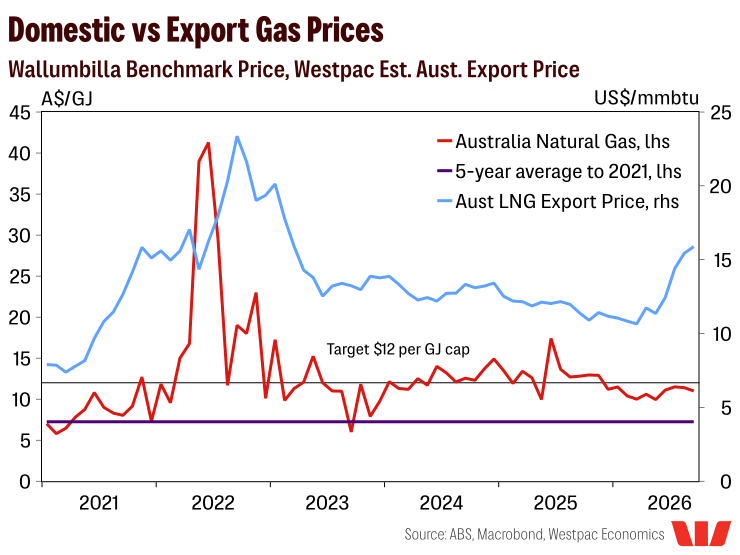
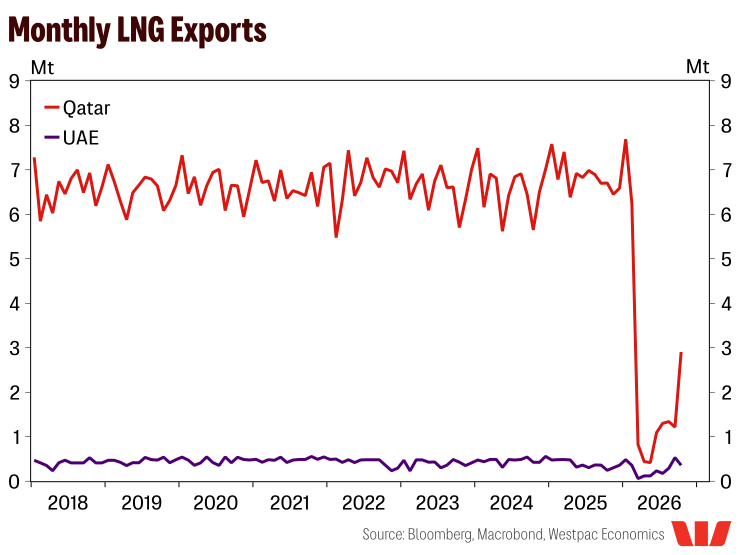
LNG prices continued to climb through October. Damage to the world’s largest LNG export complex at Ras Laffan in Qatar and the inability to divert flows around the Strait of Hormuz continue to weigh on supply. Unlike Gulf oil exports, which have increasingly utilised alternative export routes, LNG flows remain heavily constrained, with Qatar exporting only 40% of its October 2025 volumes. These constraints have been compounded by stronger competition between Northeast Asia and Europe for flexible Atlantic Basin cargoes ahead of the Northern Hemisphere winter, with European gas storage below seasonal norms. As a result, Japanese LNG prices rose 12.8%mth in October, averaging US$28.6/mmbtu. While this is more than double pre-conflict levels, demand destruction across Asia is beginning to temper the pace of gains.
Reflecting the continued acute disruption, we have raised our December quarter forecast for Japanese LNG prices to US$27.5/mmbtu. With the winter restocking period now coming to an end, the severity of the Northern Hemisphere winter and resulting demand will be key risks to the near-term outlook. Supply recovery is expected to remain constrained, with prices unlikely to return to pre-conflict levels until 2028, as new US and Qatari supply comes online. While uncertainty over current supply disruption and future oversupply is complicating negotiations over long-term LNG contract prices, Australia is well positioned to capture a reliability premium as buyers place greater value on secure supply.
Domestically, the Australian gas market remains relatively insulated, supported by the FY2027 Federal Budget’s domestic gas reservation scheme, which requires exporters to supply the equivalent of up to 20% of gas exports to the Australian market. The government’s objective remains to cap domestic gas prices at around $12/GJ which has been achieved to date despite the recent increase in LNG export price.
India increasingly underpins coal demand
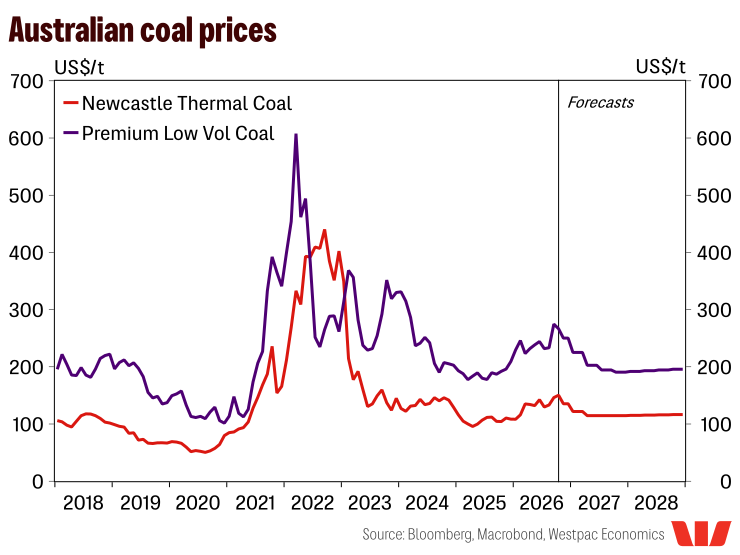
Newcastle thermal coal prices rose 2.9%mth in October, averaging US$150.2/t over the month, the highest monthly average since September 2023. Key sources of support remain in place, keeping prices well above pre-conflict levels. LNG continues to underpin the relative cost competitiveness of thermal coal, while shifting energy security priorities across Japan, South Korea and Taiwan have encouraged greater coal procurement as a hedge against LNG supply disruption, amplified by the prospect of a super El Niño. This comes amid broader global supply constraints, with diesel shortages in Mongolia and Russia restricting coal exports, while drier conditions in Indonesia curtailed barge loadings and disrupted mine-to-port logistics. India represents another source of support. Wood Mackenzie reports that coal stocks at Indian power plants were down 50%yr at end-October, with El Niño bringing hotter conditions and a weaker monsoon season, simultaneously lifting electricity demand and weighing on hydro generation. However, unfavourable import economics are limiting the resulting demand for seaborne coal.
Against this backdrop, we have slightly raised our forecast for Newcastle thermal coal to average US$135/t in the December quarter, before easing towards US$115/t through 2027 as global energy prices recede, Chinese domestic supply continues to recover following the Shanxi mining disaster and the renewable build-out advances. The pace and timing of this decline will depend heavily on progress towards a permanent US-Iran agreement and the subsequent response in LNG prices. Over the longer term, prices are expected to rise as demand outpaces supply growth, with mine depletion, regulatory hurdles, community opposition and financing constraints limiting new capacity, particularly in Australia.
Queensland premium low-vol coking coal prices softened in October, falling 3.5%mth to average US$266.2/t. The decline reflects slower Chinese steel mill procurement as participants await a recovery in domestic supply and more competitive prices. Chinese authorities moved to accelerate the resumption of coal production in Shanxi in mid-October, following output disruptions triggered by the May mine explosion and subsequent safety inspections. These directives are having a material impact with Wood Mackenzie reporting capacity utilisation at Chinese coking coal mines improved from 66% to 73% in the second half of October. Combined with lower hot-metal production and persistently weak steelmaking margins, the near-term price signal from China is increasingly negative.
India has provided a more meaningful source of support as the post-monsoon recovery lifts steel sentiment and stronger construction and manufacturing activity supports mill utilisation. However, elevated coking coal prices, compressed margins, uncertainty around global supply and rising import costs are likely to limit the overall demand impulse, leaving it insufficient to fully offset softer Chinese buying.
Looking ahead, recovering Chinese domestic supply, the normalisation of Mongolian exports as diesel shortages ease, and weak Chinese steelmaker margins are expected to weigh on seaborne demand. A recovery in Indian demand should provide some offset, although these constraints are likely to limit its strength. We expect premium low-vol coking coal prices to average US$250/t in the December quarter, before moderating further through 2027. The long-term decline in Chinese steel production and increased use of electric arc furnaces is likely to weigh on prices, while rising Indian import requirements, supported by its greater blast-furnace intensity, steel capacity expansion and urbanisation, should provide something of an offset.
Iron ore falls, but costs limit the downside
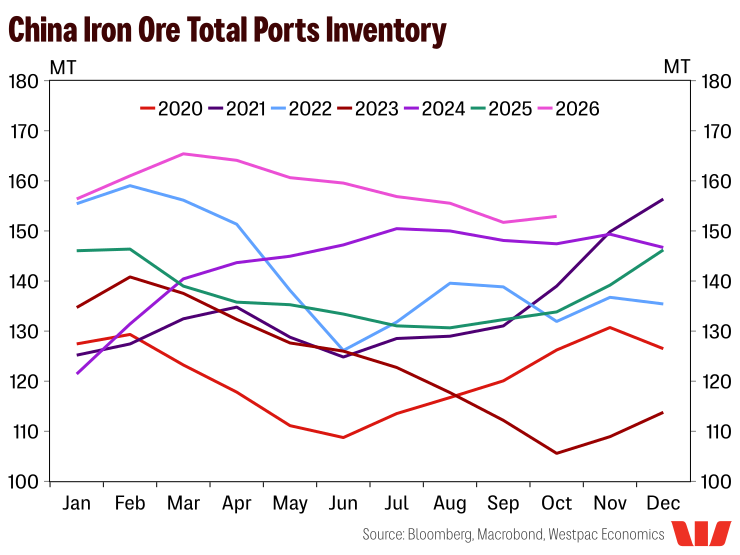
Iron ore prices (62% Fe) declined 6.1%mth in October to average US$92.3/t. Major headwinds flagged earlier are starting to bite. Seaborne supply remains robust alongside the ramp-up from Simandou in Guinea. At the same time, coking coal markets remain tight, further compressing steelmaker margins already under pressure from intense competition between mills. Wood Mackenzie reports that only 11% of Chinese mills were profitable at end-October, weighing particularly on demand for lower-grade ores. China's domestic economy also presents limited upside, with urban fixed asset investment down 8.1%ytd in October and crude steel production subdued. Against this backdrop of rising global supply and weak demand, iron ore inventories at Chinese ports increased in October and remain historically elevated.
There are, however, some areas of support. Shipping futures from Western Australia to Qingdao may have softened from recent peaks but they remain more than 55% above the 2025 average. Higher freight costs reduced the competitiveness of smaller Brazilian producers, with iron ore exports from Brazil down 8.9%yr in October. Cost pressures are also becoming increasingly evident across producer cost curves, with Wood Mackenzie estimating the 90th percentile cost of production at US$79.8/t, 5.7% above 2025 levels, while around 7% of global supply is estimated to be operating below break-even at current prices (~US$90/t). With costs expected to remain elevated through 2027, a higher industry cost base will help limit further downside (but we do note this comes via a reduction in supply). We continue to expect the 62% Fe index to average US$95/t in the December quarter.
Nevertheless, the medium-term outlook remains challenging with surplus conditions expected to emerge. Supply-side pressures are building as new low-cost output from Simandou enters the market, with Wood Mackenzie estimating export volumes could double to as much as 60Mt in 2027. Persistently high inventories in China, increased scrap usage and the structural decline in Chinese steel production are eroding underlying demand, with growth in India and South-East Asia demand a partial offset at bests. We therefore expect iron ore prices to soften further, averaging US$83/t in the December quarter of 2027. Beyond this, lower prices and increasing competition from higher-grade African and Brazilian supply are likely to weigh on Australia's iron ore export earnings. Ongoing negotiations with CMRG present an additional risk, with any sustained pressure on realised Australian iron ore prices also carrying implications for government revenue.
Gold caught between higher yields and safe-haven demand
Gold struggled through October, with prices down 5.0%mth to average US$4,105/oz. The precious metal remained under pressure from elevated real yields and a hawkish Fed amid ongoing turmoil in energy markets. As a non-yielding asset, gold has faced broader pressure throughout the conflict as markets weighed the inflationary implications of elevated energy prices and the prospect of further central bank tightening. Despite these headwinds, some pillars of support remain. Gold ETF demand has remained solid, adding 211Mt in Q3 2026, while safe-haven demand continues to be supported by a broad mix of macroeconomic and geopolitical risks and volatility surrounding the AI trade.
However, the sharp sell-off throughout November highlights the sensitivity of gold to US yields and changing expectations for monetary policy, and presents clear downside risk to our December quarter forecast of US$4,250/oz. The near-term outlook is therefore likely to remain volatile, with the path of US yields and incoming economic data critical to any recovery.
We expect a period of consolidation through 2027 as brownfield expansions at existing operations lift supply in response to recent high prices, while an elevated Fed Funds Rate limits upside for non-yielding assets. Over the longer term, structural support should persist despite continued financial-market volatility. Growing Asian participation in gold trading, investment and physical distribution should broaden the investor base, while US fiscal and currency concerns, central bank buying and reserve diversification provide underlying support.
Democrat sweep weighs on copper’s bull case
LME copper prices were relatively stable through October, easing 0.1%mth to average US$14,478/t. The pace of COMEX inventory accumulation slowed further to 2.9%mth, down from a peak of 6.7%mth in August. This followed reports in September that a US decision on Section 232 tariffs had stalled amid concerns that higher copper prices would add to manufacturing costs. Even so, the continued pull of material into the US contributed to tightness elsewhere, with the LME prompt-to-three-month backwardation remaining elevated through October.
Supply disruptions in Chile provided further support. Accounting for around a quarter of global copper production, Chile has faced a series of setbacks, including two fatal accidents at separate operations that resulted in production suspensions, alongside severe weather associated with the ongoing El Niño pattern. Declining ore grades and increasing ore complexity have added to these pressures. These supply constraints, together with the broader electrification trend, supported copper through October. However, a weaker macroeconomic outlook, persistently elevated energy costs and a sharp rotation out of the copper-linked AI trade offset these gains, leaving prices broadly unchanged over the month.
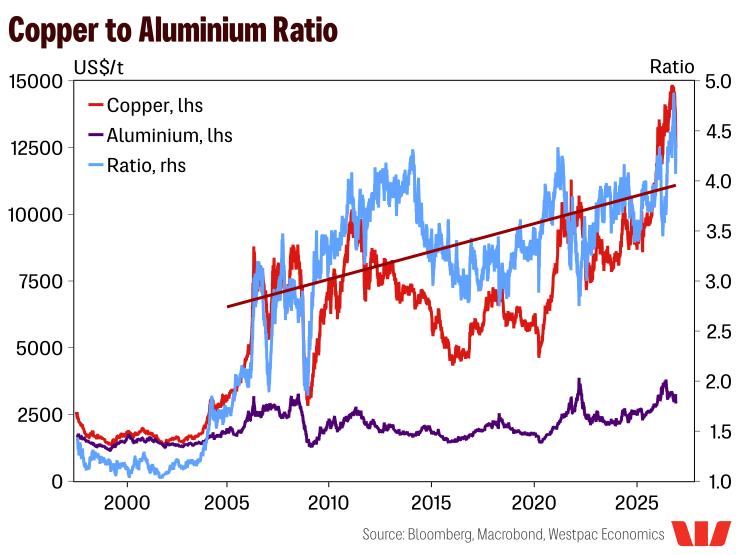
Moving into November, headwinds have continued to build as several recent sources of support come under pressure. The major shift was the US midterm elections and the Democratic sweep of Congress and gaining a majority in the Senate. The initial reaction across equity markets saw the AI trade pull back on concerns that a Democrat-controlled Congress could impose greater regulatory constraints on infrastructure build-out. Copper's links to AI made it a casualty of the broader sell-off, with LME prices falling sharply at the start of the month. Democratic control of Congress has also reduced the risk of more severe Section 232 tariff implementation, although it has not been removed entirely. A historically elevated copper-to-aluminium price ratio presents an additional headwind by increasing the incentive for substitution where feasible. Against this backdrop, we have downgraded our near-term LME copper forecast, with prices expected to average US$14,000/t in Q4. Ongoing electrification following the latest energy shock, together with AI and data-centre investment outside the US, should continue to underpin demand, while cautious COMEX inventory accumulation is likely to persist.
The medium-term outlook is unlikely to provide significant upside for copper prices. The eventual outcome of the Section 232 review is expected to weigh on the market as US inventory accumulation comes to an end. However, a softer demand impulse appears more likely than a sharp drawdown in inventories, with much of the accumulated stock expected to be consumed domestically. China's property sector also remains under pressure, with fixed asset investment falling 7.2%ytd in September, while additional mine supply should add to downward pressure on prices.
However, structural demand from electrification and manufacturing localisation should provide a floor, with prices expected to trough at around US$12,810/t by early 2029. Beyond this point, we expect prices to strengthen considerably as net-zero targets approach, EV adoption gathers pace, renewable deployment accelerates and rising data-centre investment drives additional demand for power generation and transmission infrastructure.
For Australia, the structural rise in copper demand and prices should support a gradual diversification of the export mix, reducing its exposure to China's steel cycle.
Aluminium prices move ahead of the physical recovery
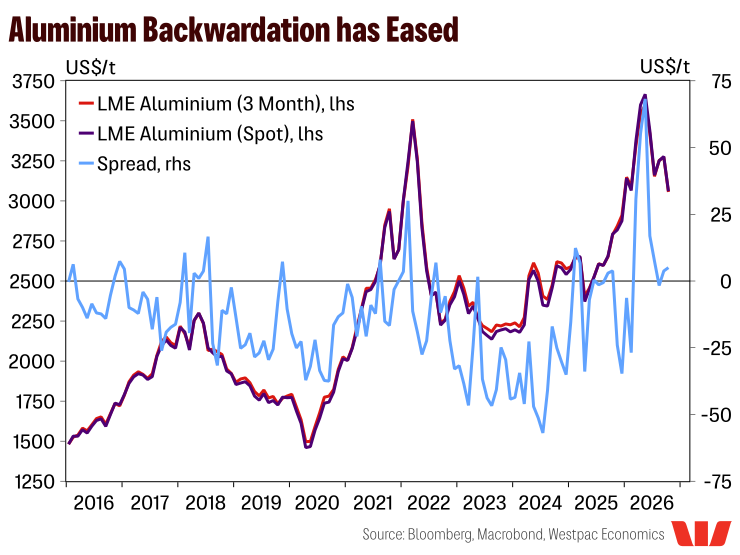
Aluminium prices fell 6.5%mth in October to average US$3,069/t, reflecting a stronger US dollar, expectations of a relatively rapid recovery in Middle Eastern production and new supply from Indonesia. However, markets may have moved ahead of the physical recovery, with LME backwardation widening through October and signalling continued near-term tightness.
Disruption to Gulf smelting capacity remains a significant constraint, with the region accounting for around 9% of global capacity and a considerably larger share of global trade. While production is recovering, extended delivery times and difficulties securing sufficient alumina feedstock continue to constrain output. Indeed, IAI data show Gulf Cooperation Council production in September remained 39.5% below September 2025 levels. Given the time- and capital-intensive nature of restarting smelting capacity, we expect tightness to persist through the remainder of 2026. Emirates Global Aluminium (EGA) remains on track for a full restart at Al Taweelah by Q1 2027, while Alba in Bahrain was last reported to be operating 20% below capacity.
China is unlikely to fully offset these losses. Aluminium production increased just 2.9%yr in September, replacing only around half of the lost GCC output. Further gains are constrained by already-high utilisation rates and China's capacity replacement policy, which requires new capacity to be matched by the permanent closure of existing approved capacity. Meanwhile, although energy prices have fallen materially in November, they remain well above pre-conflict levels and should continue to support aluminium prices given the electricity-intensive nature of smelting..
Alumina markets are adding to these pressures, with prices approaching US$400/t in early November on incremental demand from Middle Eastern and Indonesian smelters and earlier production cuts at key suppliers. Alcoa has lowered its 2026 alumina production guidance by 200–300kt following operational disruptions at one of its Western Australian refineries, while Alunorte has reduced output by 100–120kt following earlier disruptions to gas supply. Importantly, this international tightness contrasts with structural oversupply in China's domestic alumina market, even as Chinese aluminium smelters operate near full capacity.
Against this backdrop, we expect aluminium prices to remain relatively supported through the remainder of 2026, although we have slightly downgraded our forecast. Higher prices are incentivising capacity restarts across Western economies and South-East Asia, while Chinese aluminium demand remains subdued. Falling copper prices have also reduced the copper-to-aluminium price ratio, lowering the incentive to substitute towards aluminium where feasible. We therefore forecast aluminium to average US$3,230/t in the December quarter. Thereafter, prices are expected to ease as Gulf production recovers and new Indonesian smelting capacity backed by Chinese investment comes online. Longer-term support should come from EV, grid infrastructure and data-centre investment, although growing competition for power from data centres may constrain future smelting capacity expansion.
Jianxiawo approval weighs on lithium
Lithium was the weakest performer across the commodities complex in October, as persistent oversupply concerns weighed on sentiment. CATL’s Jianxiawo mine, which at full capacity accounts for around 3–4% of global lithium supply, received environmental approval at the end of the month, reinforcing expectations of ample supply. This followed last month’s decision by China’s Ministry of Industry and Information Technology to freeze approvals for greenfield power and battery energy storage system (BESS) factories yet to break ground, adding to concerns around the demand outlook. Against this backdrop, spodumene (6% FOB Australia) prices fell 26.1%mth in October to US$1,484/t.
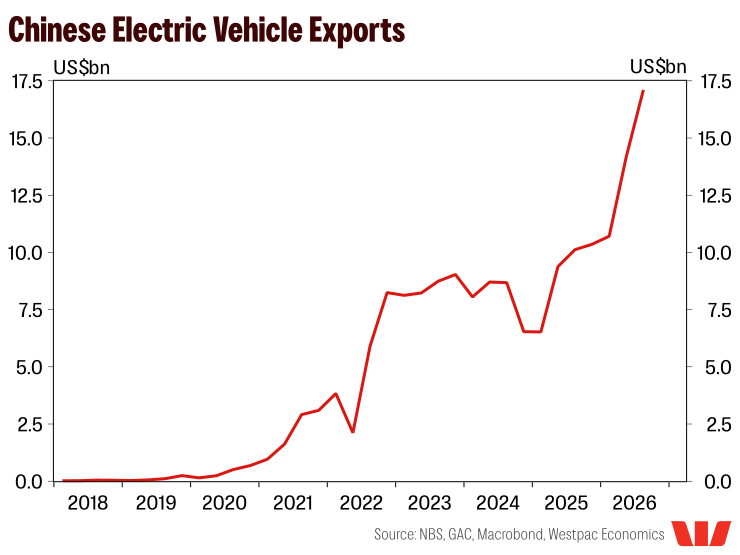
Idled capacity developed during the previous lithium price boom remains a near-term headwind, limiting the scope for a sustained price recovery. However, the underlying demand story remains constructive. Investment in energy storage remains strong following the recent energy shock, while EV adoption continues to accelerate. The IEA projects electric vehicles will account for 28% of global vehicle sales in 2026, while lower-cost Chinese EVs continue to gain market share, having accounted for 60% of global EV sales in 2025.
Over the medium to longer term, additional supply, particularly from Australia, is expected to place further downward pressure on prices. Recent tax changes in China, which impose a consumption tax on lithium-ion batteries while exempting sodium-ion and solid-state batteries until end-2028, may also encourage some substitution away from lithium at the margin. Nevertheless, lithium is expected to remain the dominant battery chemistry, with demand underpinned by structural electrification trends. EVs will remain the primary source of demand, while BESS growth should accelerate alongside renewable generation and rising data-centre power requirements.
Lithium is also becoming increasingly strategically important as Western economies seek to diversify critical mineral supply chains. Australia is well positioned as a key supplier of lithium feedstock and battery materials, although expanding domestic production means the benefits are likely to come through higher export volumes rather than materially higher prices.
Stay informed with Westpac IQ
Get the latest reports straight to your inbox.
Related articles
Commodities Update October 2026
Commodities Update September 2026
Commodities Update August 2026
Browse topics
Disclaimer
©2026 Westpac Banking Corporation ABN 33 007 457 141 (including where acting under any of its Westpac, St George, Bank of Melbourne or BankSA brands, collectively, “Westpac”). References to the “Westpac Group” are to Westpac and its subsidiaries and includes the directors, employees and representatives of Westpac and its subsidiaries.
Things you should know
We respect your privacy: You can view the New Zealand Privacy Policy here, or the Australian Group Privacy Statement here. Each time someone visits our site, data is captured so that we can accurately evaluate the quality of our content and make improvements for you. We may at times use technology to capture data about you to help us to better understand you and your needs, including potentially for the purposes of assessing your individual reading habits and interests to allow us to provide suggestions regarding other reading material which may be suitable for you.
This information, unless specifically indicated otherwise, is under copyright of the Westpac Group. None of the material, nor its contents, nor any copy of it, may be altered in any way, transmitted to, copied of distributed to any other party without the prior written permission of the Westpac Group.
Disclaimer
This information has been prepared by Westpac and is intended for information purposes only. It is not intended to reflect any recommendation or financial advice and investment decisions should not be based on it. This information does not constitute an offer, a solicitation of an offer, or an inducement to subscribe for, purchase or sell any financial instrument or to enter into a legally binding contract. To the extent that this information contains any general advice, it has been prepared without taking into account your objectives, financial situation or needs and before acting on it you should consider the appropriateness of the advice. Certain types of transactions, including those involving futures, options and high yield securities give rise to substantial risk and are not suitable for all investors. We recommend that you seek your own independent legal or financial advice before proceeding with any investment decision.
This information may contain material provided by third parties. While such material is published with the necessary permission none of Westpac or its related entities accepts any responsibility for the accuracy or completeness of any such material. Although we have made every effort to ensure this information is free from error, none of Westpac or its related entities warrants the accuracy, adequacy or completeness of this information, or otherwise endorses it in any way. Except where contrary to law, Westpac Group intend by this notice to exclude liability for this information. This information is subject to change without notice and none of Westpac or its related entities is under any obligation to update this information or correct any inaccuracy which may become apparent at a later date. This information may contain or incorporate by reference forward-looking statements. The words “believe”, “anticipate”, “expect”, “intend”, “plan”, “predict”, “continue”, “assume”, “positioned”, “may”, “will”, “should”, “shall”, “risk” and other similar expressions that are predictions of or indicate future events and future trends identify forward-looking statements. These forward-looking statements include all matters that are not historical facts. Past performance is not a reliable indicator of future performance, nor are forecasts of future performance. Whilst every effort has been taken to ensure that the assumptions on which any forecasts are based are reasonable, the forecasts may be affected by incorrect assumptions or by known or unknown risks and uncertainties. The ultimate outcomes may differ substantially from any forecasts.
Conflicts of Interest: In the normal course of offering banking products and services to its clients, the Westpac Group may act in several capacities (including issuer, market maker, underwriter, distributor, swap counterparty and calculation agent) simultaneously with respect to a financial instrument, giving rise to potential conflicts of interest which may impact the performance of a financial instrument. The Westpac Group may at any time transact or hold a position (including hedging and trading positions) for its own account or the account of a client in any financial instrument which may impact the performance of that financial instrument.
Author(s) disclaimer and declaration: The author(s) confirms that (a) no part of his/her compensation was, is, or will be, directly or indirectly, related to any views or (if applicable) recommendations expressed in this material; (b) this material accurately reflects his/her personal views about the financial products, companies or issuers (if applicable) and is based on sources reasonably believed to be reliable and accurate; (c) to the best of the author’s knowledge, they are not in receipt of inside information and this material does not contain inside information; and (d) no other part of the Westpac Group has made any attempt to influence this material.
Further important information regarding sustainability-related content: This material may contain statements relating to environmental, social and governance (ESG) topics. These are subject to known and unknown risks, and there are significant uncertainties, limitations, risks and assumptions in the metrics, modelling, data, scenarios, reporting and analysis on which the statements rely. In particular, these areas are rapidly evolving and maturing, and there are variations in approaches and common standards and practice, as well as uncertainty around future related policy and legislation. Some material may include information derived from publicly available sources that have not been independently verified. No representation or warranty is made as to the accuracy, completeness or reliability of the information. There is a risk that the analysis, estimates, judgements, assumptions, views, models, scenarios or projections used may turn out to be incorrect. These risks may cause actual outcomes to differ materially from those expressed or implied. The ESG-related statements in this material do not constitute advice, nor are they guarantees or predictions of future performance, and Westpac gives no representation, warranty or assurance (including as to the quality, accuracy or completeness of the statements). You should seek your own independent advice.
Additional country disclosures:
Australia: Westpac holds an Australian Financial Services Licence (No. 233714). You can access Westpac’s Financial Services Guide here or request a copy from your Westpac point of contact. To the extent that this information contains any general advice, it has been prepared without taking into account your objectives, financial situation or needs and before acting on it you should consider the appropriateness of the advice.
New Zealand: In New Zealand, Westpac Institutional Bank refers to the brand under which products and services are provided by either Westpac (NZ division) or Westpac New Zealand Limited (company number 1763882), the New Zealand incorporated subsidiary of Westpac ("WNZL"). Any product or service made available by WNZL does not represent an offer from Westpac or any of its subsidiaries (other than WNZL). Neither Westpac nor its other subsidiaries guarantee or otherwise support the performance of WNZL in respect of any such product. WNZL is not an authorised deposit-taking institution for the purposes of Australian prudential standards. The current disclosure statements for the New Zealand branch of Westpac and WNZL can be obtained at the internet address www.westpac.co.nz.
Singapore: This material has been prepared and issued for distribution in Singapore to institutional investors, accredited investors and expert investors (as defined in the applicable Singapore laws and regulations) only. Recipients of this material in Singapore should contact Westpac Singapore Branch in respect of any matters arising from, or in connection with, this material. Westpac Singapore Branch holds a wholesale banking licence and is subject to supervision by the Monetary Authority of Singapore.
Fiji: Unless otherwise specified, the products and services for Westpac Fiji are available from www.westpac.com.fj © Westpac Banking Corporation ABN 33 007 457 141. This information does not take your personal circumstances into account and before acting on it you should consider the appropriateness of the information for your financial situation. Westpac Banking Corporation ABN 33 007 457 141 is incorporated in NSW Australia and registered as a branch in Fiji. The liability of its members is limited.
Papua New Guinea: Unless otherwise specified, the products and services for Westpac PNG are available from www.westpac.com.pg © Westpac Banking Corporation ABN 33 007 457 141. This information does not take your personal circumstances into account and before acting on it you should consider the appropriateness of the information for your financial situation. Westpac Banking Corporation ABN 33 007 457 141 is incorporated in NSW Australia. Westpac is represented in Papua New Guinea by Westpac Bank - PNG - Limited. The liability of its members is limited.
U.S.: Westpac operates in the United States of America as a federally licensed branch, regulated by the Office of the Comptroller of the Currency. Westpac is also registered with the US Commodity Futures Trading Commission (“CFTC”) as a Swap Dealer, but is neither registered as, or affiliated with, a Futures Commission Merchant registered with the US CFTC. The services and products referenced above are not insured by the Federal Deposit Insurance Corporation (“FDIC”). Westpac Capital Markets, LLC (‘WCM’), a wholly-owned subsidiary of Westpac, is a broker-dealer registered under the U.S. Securities Exchange Act of 1934 (‘the Exchange Act’) and member of the Financial Industry Regulatory Authority (‘FINRA’). In accordance with APRA's Prudential Standard 222 'Association with Related Entities', Westpac does not stand behind WCM other than as provided for in certain legal agreements between Westpac and WCM and obligations of WCM do not represent liabilities of Westpac.
This communication is provided for distribution to U.S. institutional investors in reliance on the exemption from registration provided by Rule 15a-6 under the Exchange Act and is not subject to all of the independence and disclosure standards applicable to debt research reports prepared for retail investors in the United States. WCM is the U.S. distributor of this communication and accepts responsibility for the contents of this communication. Transactions by U.S. customers of any securities referenced herein should be effected through WCM. All disclaimers set out with respect to Westpac apply equally to WCM. If you would like to speak to someone regarding any security mentioned herein, please contact WCM on +1 212 389 1269. Investing in any non-U.S. securities or related financial instruments mentioned in this communication may present certain risks. The securities of non-U.S. issuers may not be registered with, or be subject to the regulations of, the SEC in the United States. Information on such non-U.S. securities or related financial instruments may be limited. Non-U.S. companies may not be subject to audit and reporting standards and regulatory requirements comparable to those in effect in the United States. The value of any investment or income from any securities or related derivative instruments denominated in a currency other than U.S. dollars is subject to exchange rate fluctuations that may have a positive or adverse effect on the value of or income from such securities or related derivative instruments.
The author of this communication is employed by Westpac and is not registered or qualified as a research analyst, representative, or associated person of WCM or any other U.S. broker-dealer under the rules of FINRA, any other U.S. self-regulatory organisation, or the laws, rules or regulations of any State. Unless otherwise specifically stated, the views expressed herein are solely those of the author and may differ from the information, views or analysis expressed by Westpac and/or its affiliates.
UK: The London branch of Westpac is authorised in the United Kingdom by the Prudential Regulation Authority (PRA) and is subject to regulation by the Financial Conduct Authority (FCA) and limited regulation by the PRA (Financial Services Register number: 124586). The London branch of Westpac is registered at Companies House as a branch established in the United Kingdom (Branch No. BR000106). Details about the extent of the regulation of Westpac’s London branch by the PRA are available from us on request.
This communication is not being made to or distributed to, and must not be passed on to, the general public in the United Kingdom. Rather, this communication is being made only to and is directed at (a) those persons falling within the definition of Investment Professionals (set out in Article 19(5) of the Financial Services and Markets Act 2000 (Financial Promotion) Order 2005 (the “Order”)); (b) those persons falling within the definition of high net worth companies, unincorporated associations etc. (set out in Article 49(2)of the Order; (c) other persons to whom it may lawfully be communicated in accordance with the Order or (d) any persons to whom it may otherwise lawfully be made (all such persons together being referred to as “relevant persons”). Any person who is not a relevant person should not act or rely on this communication or any of its contents. In the same way, the information contained in this communication is intended for “eligible counterparties” and “professional clients” as defined by the rules of the Financial Conduct Authority and is not intended for “retail clients”. Westpac expressly prohibits you from passing on the information in this communication to any third party.
European Economic Area (“EEA”): This material may be distributed to you by either: (i) Westpac directly, or (ii) Westpac Europe GmbH (“WEG”) under a sub-licensing arrangement. WEG has not edited or otherwise modified the content of this material. WEG is authorised in Germany by the Federal Financial Supervision Authority (‘BaFin’) and subject to its regulation. WEG’s supervisory authorities are BaFin and the German Federal Bank (‘Deutsche Bundesbank’). WEG is registered with the commercial register (‘Handelsregister’) of the local court of Frankfurt am Main under registration number HRB 118483. In accordance with APRA’s Prudential Standard 222 ‘Association with Related Entities’, Westpac does not stand behind WEG other than as provided for in certain legal agreements (a risk transfer, sub-participation and collateral agreement) between Westpac and WEG and obligations of WEG do not represent liabilities of Westpac. Any product or service made available by WEG does not represent an offer from Westpac or any of its subsidiaries (other than WEG). All disclaimers set out with respect to Westpac apply equally to WEG.
This communication is not intended for distribution to, or use by any person or entity in any jurisdiction or country where such distribution or use would be contrary to local law or regulation.
This communication contains general commentary, research, and market colour. The communication does not constitute investment advice. The material may contain an ‘investment recommendation’ and/or ‘information recommending or suggesting an investment’, both as defined in Regulation (EU) No 596/2014 (including as applicable in the United Kingdom) (“MAR”). In accordance with the relevant provisions of MAR, reasonable care has been taken to ensure that the material has been objectively presented and that interests or conflicts of interest of the sender concerning the financial instruments to which that information relates have been disclosed.
Investment recommendations must be read alongside the specific disclosure which accompanies them and the general disclosure which can be found here. Such disclosure fulfils certain additional information requirements of MAR and associated delegated legislation and by accepting this communication you acknowledge that you are aware of the existence of such additional disclosure and its contents.
To the extent this communication comprises an investment recommendation it is classified as non-independent research. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and therefore constitutes a marketing communication. Further, this communication is not subject to any prohibition on dealing ahead of the dissemination of investment research.